If you’ve been reading about PMEGP Scheme and still aren’t sure how the subsidy actually gets calculated or whether you even qualify, you’re not alone. Most explanations either drown you in scheme jargon or skip the one thing you actually want to know: what does this look like with real numbers, for a project like mine?
This guide walks through it properly. At Sharda Associates, we prepare CA-certified project reports for PMEGP applicants every week, so we see exactly where people get confused and where a genuinely good application still goes wrong. If you get stuck at any point here, our team is happy to walk through your specific numbers with you.
What Is PMEGP, in Plain Terms
PMEGP stands for Prime Minister’s Employment Generation Programme. It’s a government scheme that helps you set up a new micro-enterprise by combining three things: a bit of money you put in yourself, a bank loan, and a government subsidy that permanently reduces how much of that loan you actually have to repay.
The scheme is run by the Khadi and Village Industries Commission, or KVIC, under the Ministry of MSME. It’s meant for new units only, not for expanding a business you’re already running.
Who Can Actually Apply
- You need to be at least 18 years old. There’s no upper age limit and no income ceiling.
- If your manufacturing project costs more than ₹10 lakh, or your service project costs more than ₹5 lakh, you need to have passed at least the 8th standard.
- Self-help groups, cooperative societies, and charitable trusts can apply too, not just individuals.
- The project has to be new. If you already run the business and are just expanding it, this scheme isn’t for you, though a separate upgrade route exists for that; more on this below.
Project Cost Limits
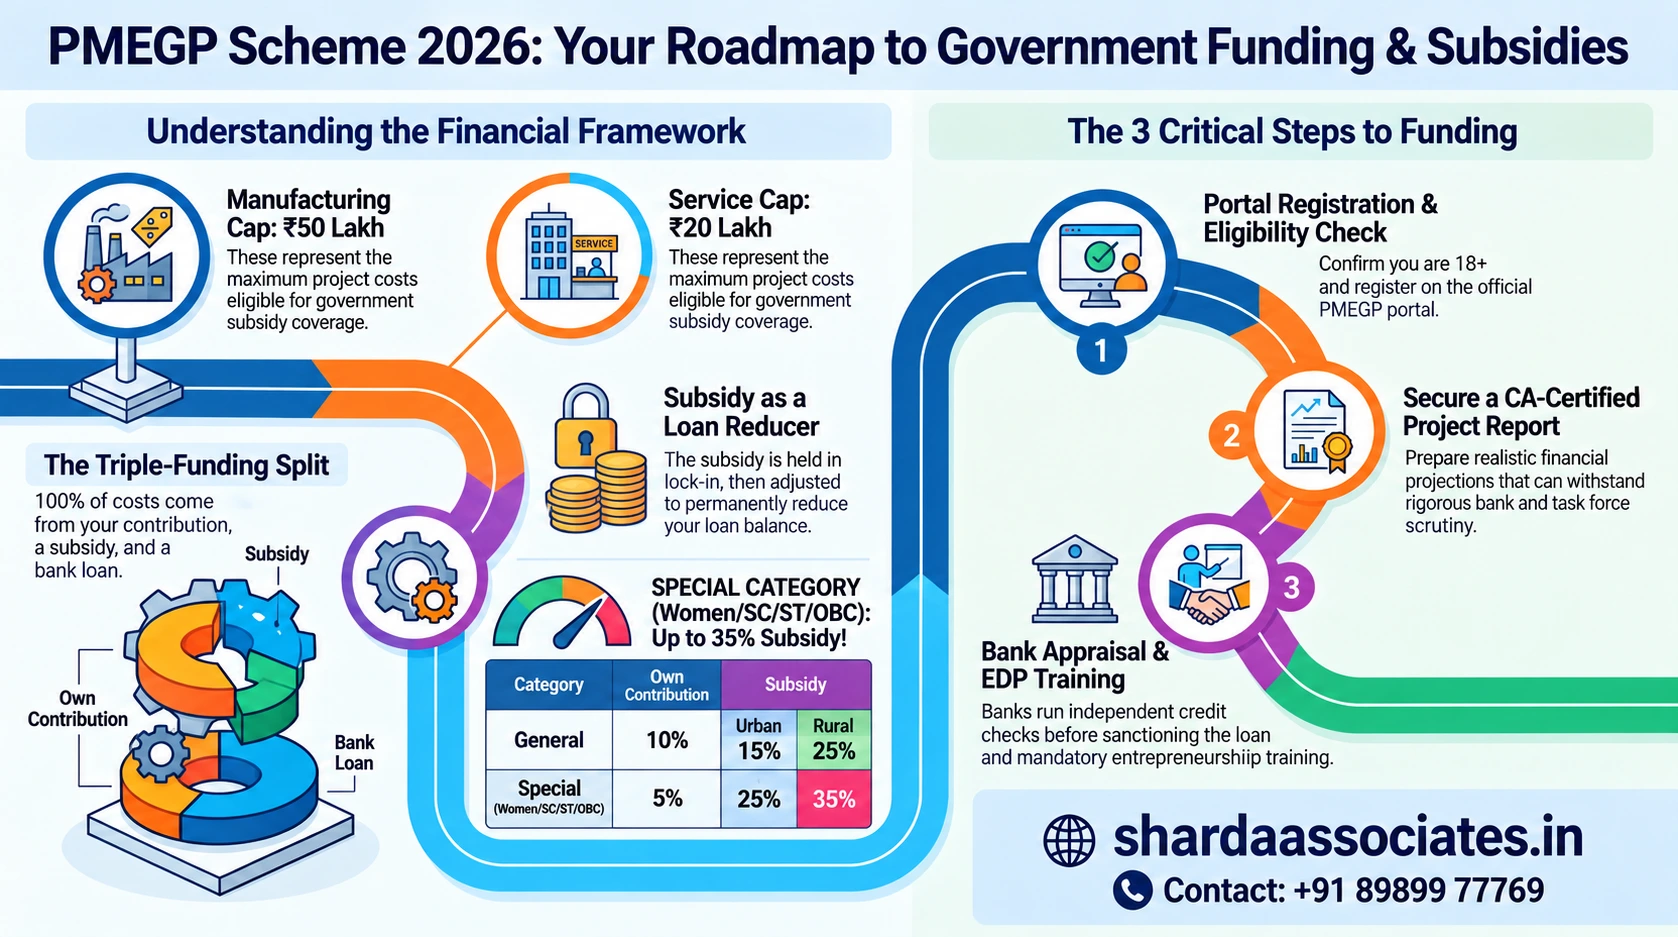
| Sector | Maximum Eligible Project Cost |
| Manufacturing | ₹50 lakh |
| Service or Business | ₹20 lakh |
These are the ceilings for what qualifies for subsidy. You can propose a larger project, but anything above these limits doesn’t get subsidy cover and shifts entirely onto the bank loan, at the bank’s discretion.
How the Subsidy Actually Works
This is the part most explanations rush through. Your project cost is split into exactly three pieces, and they always add up to 100%.
| Category | Your Own Contribution | Subsidy (Urban) | Subsidy (Rural) |
| General | 10% | 15% | 25% |
| Special (SC/ST/OBC/Women/Minorities/Ex-Servicemen/NER/Hill Areas) | 5% | 25% | 35% |
Whatever’s left after your contribution and the subsidy is financed as a bank loan.
A worked example. Say you’re setting up a service business with a project cost of ₹20 lakh, you fall under the general category, and your unit is in a rural area.
- Your own contribution (10%): ₹2 lakh
- Government subsidy (25%): ₹5 lakh
- Bank loan (the remaining 65%): ₹13 lakh
You only repay EMI on the ₹13 lakh loan. The ₹5 lakh subsidy isn’t a loan you pay back; it’s held in a special account for a lock-in period and then adjusted directly against your loan balance, permanently reducing what you owe.
If You Already Have a PMEGP Unit: The Upgradation Route
If you’ve already availed a PMEGP, REGP, or Mudra loan and want to expand that existing unit, there’s a separate track for you. The subsidy here is lower, generally 15% (20% in NER and hill states), and your own contribution stays at 10%. This is genuinely useful and often overlooked, since a lot of applicants assume PMEGP is a one-time-only door that shuts once they’ve used it.
How to Apply For PMEGP Scheme: The Actual Steps
- Confirm your eligibility and pick your activity. Check that your business idea isn’t on the scheme’s negative list and that it fits either the manufacturing or service category correctly.
- Register and fill out the application on the PMEGP portal at pmegp.msme.gov.in. You’ll need your Aadhaar, basic KYC documents, and details of the proposed project.
- Prepare your project report. This is where a generic template usually falls short. Your report needs a realistic cost estimate, means of finance, and financial projections that a bank will actually check, not just numbers that look fine on the surface.
- Submit and wait for scrutiny. Your application gets scored against a fixed set of parameters. Only applications above the minimum threshold get forwarded to a bank.
- Attend the interview, if your case involves one. For many applications, a task force checks whether you actually understand your own project, not just whether the report reads well.
- Bank appraisal. The bank runs its own credit check, independent of the scheme’s scrutiny, looking at your credit history, the project’s repayment capacity, and your documentation.
- Sanction and EDP training. Once sanctioned, you’ll typically go through Entrepreneurship Development Programme training before or alongside your first disbursement.
- Disbursement. Your bank loan gets disbursed, and the subsidy amount is credited into a linked account, to be adjusted after the lock-in period.
Where This Tends to Go Wrong
Two things account for most of the friction we see. First, a project report that doesn’t hold up under bank scrutiny, unrealistic revenue assumptions, no real DSCR workings, or numbers that don’t match the applicant’s actual situation. Second, applicants who genuinely don’t know their own numbers well enough to explain them if a Task Force interview is involved.
If your application has already gone through and stalled or come back rejected, we’ve written specifically about why PMEGP applications get rejected even after reaching the bank and separately about the mistakes applicants most often make, if either sounds like where you’re stuck.
Conclusion
PMEGP is a genuinely useful scheme once you understand how the three pieces, your contribution, the subsidy, and the bank loan, actually fit together for your specific project cost. The application process itself isn’t complicated. What trips people up is usually the project report underneath it.
At Sharda Associates, we build CA-certified PMEGP project reports specifically to hold up at both the scrutiny stage and the bank’s own appraisal. Call us at +91 89899 77769 or reach out through our contact form, and we’ll work through your numbers with you.
Frequently Asked Questions
1. I run a small existing business. Can I still apply for PMEGP?
Not for the same business as a “new” project. PMEGP funds new units only. If you’ve already availed a PMEGP, REGP, or Mudra loan and want to expand, the upgradation route applies instead, with a 15% subsidy (20% in NER and hill areas).
2. My project cost is ₹30 lakh but I’m not sure which category it falls under. How do I decide?
If you’re producing or making something, it’s manufacturing, with a ₹50 lakh ceiling. If you’re providing a service, repair, consultancy, or salon, it falls under services, capped at ₹20 lakh. Get this right before applying, since it affects both your ceiling and the education requirement.
3. Will I actually get the subsidy amount in my hand?
No, and this trips people up. The subsidy is held in a linked account for a lock-in period and then adjusted against your loan, reducing what you owe. It’s not paid to you directly.
4. What if my project cost is higher than the ceiling for my sector?
You can still propose it, but only the amount up to the ceiling gets subsidy cover. Anything above that is financed purely through the bank loan, at the bank’s discretion.
5. I don’t have a passed 8th standard certificate. Can I still apply?
Yes, as long as your project cost stays below ₹10 lakh for manufacturing or ₹5 lakh for services. Above those thresholds, the education requirement applies.
6. My bank hasn’t responded to my forwarded application in weeks. What do I do?
This is common and usually isn’t a rejection, it’s inaction. Visit the branch directly with your application reference, and if there’s no movement, ask the sponsoring agency about routing the file to a different bank.
7. Can I choose which bank my PMEGP application goes to?
Generally yes, you can express a preference during application. It genuinely helps to pick a branch with an active PMEGP processing history rather than one unfamiliar with the scheme.
8. Does a weak CIBIL score disqualify me automatically?
Not automatically, but below roughly 650, most banks get considerably more cautious, and it’s one of the more common reasons a technically eligible application still gets stuck. Worth checking your score before you apply.
9. How is the subsidy percentage actually decided for my case?
It depends on two things together, your category (general or special) and whether your unit is urban or rural. Both matter, not just one.
10. Do I need a professionally prepared project report, or can I write it myself?
You can draft one yourself, but most rejections and stalled files trace back to a report that doesn’t hold up at bank appraisal or the Task Force interview stage. A CA-certified report built around your actual numbers is what most applicants end up needing regardless.