Short answer: The existing cash credit limit does not increase on its own. When a business expands, its stock and receivables usually grow, so it needs more working capital. You have to ask the bank for an enhancement, and the bank will reassess the limit based on your new projections, past performance and account conduct.
Introduction
When a business expands, the cash credit limit that was enough earlier often becomes too small. More production means more raw material, more stock and more money stuck with customers. Many owners notice this only when the account keeps touching the limit and payments get delayed.
Banks do not raise a limit automatically because your factory got bigger. They want to see that the growth is real and that the extra money will be used for the business and come back through sales.
At Sharda Associates, we prepare CA-certified project reports and CMA data, and we help MSMEs with bank loan documentation. In this guide, we explain what happens to your CC limit during expansion, how banks decide on an enhancement, and what you should keep ready.
Does My Cash Credit Limit Increase Automatically When I Expand?
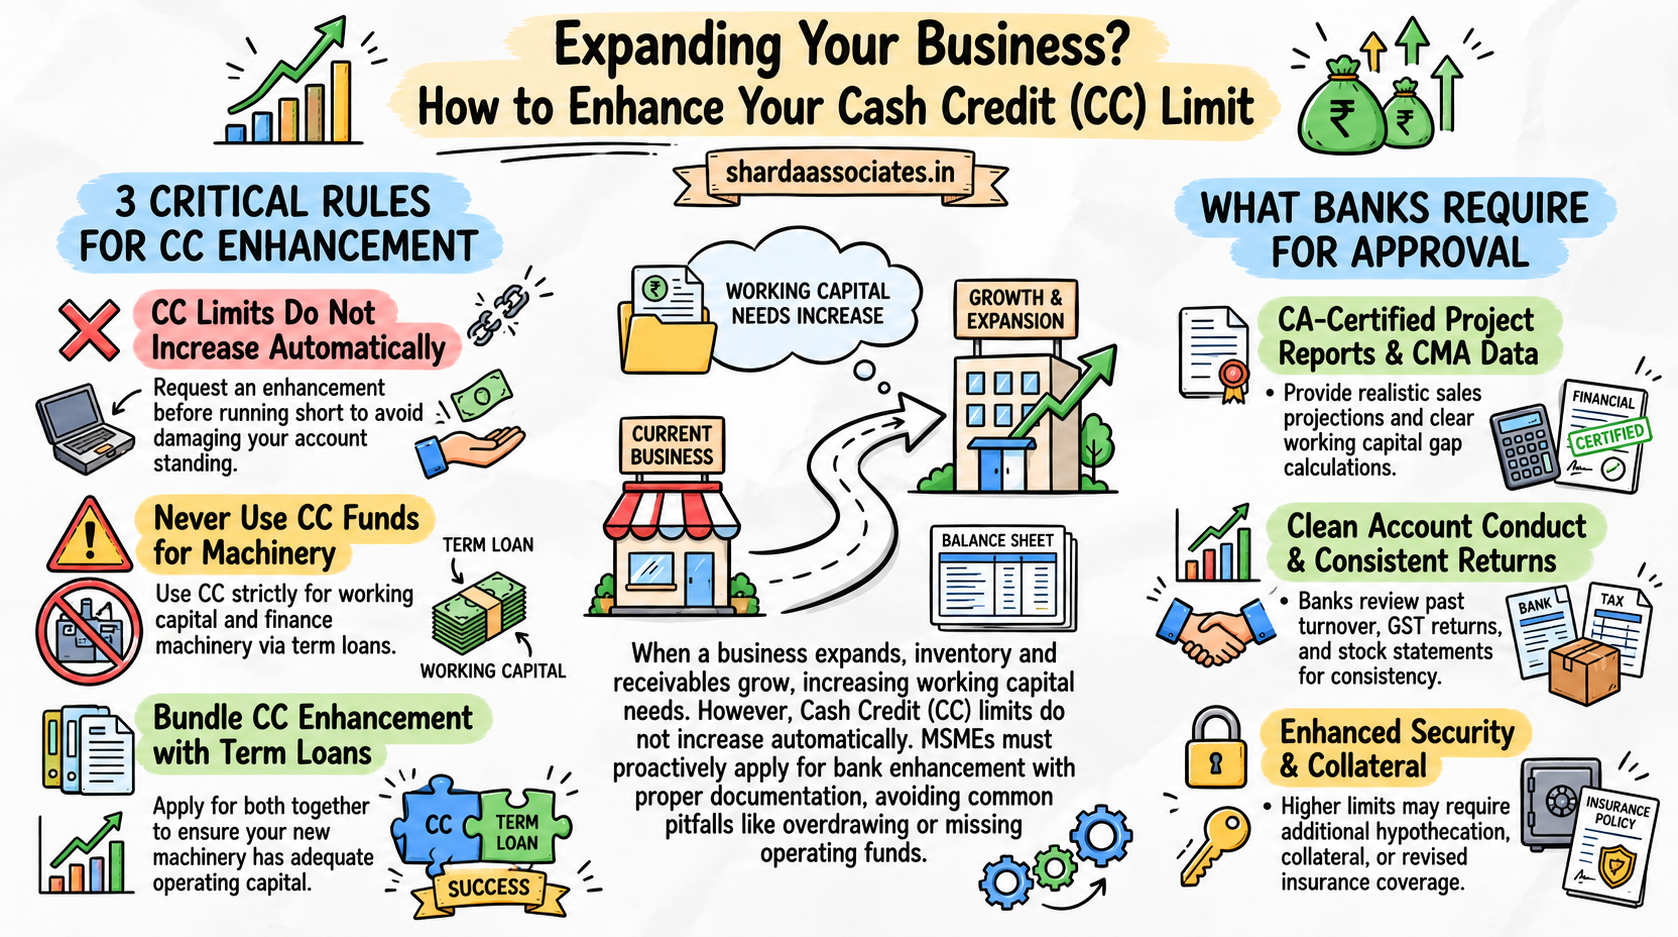
No. The limit stays the same until the bank formally sanctions a higher amount. Using more than your limit or drawing power can make the account irregular, which hurts your chances of getting an enhancement later.
- The sanctioned limit stays fixed until reviewed
- Overdrawing creates irregularity in the account
- Ask for enhancement before you run short, not after
Why Does an Expanding Business Need More Working Capital?
More capacity means higher purchases of raw material, more finished goods in stock and bigger credit given to customers. All of this blocks more cash. The enhancement request should be based on this actual growth in your operating cycle.
- Larger raw material purchases
- Higher stock of finished goods
- More sales on credit
- Possible longer payment cycles with bigger buyers
How Does the Bank Decide the Enhanced Limit?
The bank looks at the same logic as the first limit, but now it also has your track record. It compares your projections with the actual performance of the past period.
- Your projected sales and working capital gap after expansion
- Past turnover and how the account was operated
- Stock statements and GST returns
- Your margin contribution
- The quality of the expansion plan
Should I Apply for Enhancement Together With the Term Loan?
If the expansion involves new machinery, it is usually better to apply for the term loan and the working capital enhancement together. The bank can then assess the whole project and see that the new capacity will have enough working capital to run.
- One combined project report is easier to assess
- Separate requests can lead to mismatches in figures
- The bank can fix the margin for both parts together
Can I Use My Existing Cash Credit Limit to Buy New Machinery?
No. A cash credit limit is meant for day-to-day operations such as raw material and stock. Using it to buy machinery locks your money for a long time and can make the account irregular. The bank may treat this as diversion of funds.
- Use CC only for working capital
- Use a term loan for machinery
- If machinery is needed, apply for the right facility
What Documents Will the Bank Ask For?
The bank wants proof that the business has actually grown or will grow. Keep your records consistent, because mismatches slow down the process.
- Updated project report and CMA data
- Recent financial statements and GST returns
- Stock and debtors statements
- Bank account statements
- Orders or contracts supporting the projected sales
- Details of the expansion and any new loan
What Happens to Security When the Limit Is Enhanced?
A higher limit may need more security, because the bank’s exposure increases. The bank may ask for a larger charge on current assets, additional collateral or a revised guarantee, as per its policy.
- Hypothecation of the increased stock and receivables
- Additional collateral, if required
- Revised insurance for the higher stock value
Example: A Growing Garment Manufacturer
A garment unit has a cash credit limit that was sanctioned when it had a small order base. After installing new machines, orders from a large buyer increase, and the unit begins to buy more fabric. Soon the account keeps touching the limit.
The owner applies for an enhancement with updated CMA data, recent stock statements, GST returns and the buyer’s purchase orders. The bank studies the account conduct, compares the projections with actual sales and sanctions a higher limit, with a revised drawing power and updated insurance.
Had the owner waited until the account became irregular, the bank might have been less willing.
Conclusion
When a business expands, the cash credit limit does not rise by itself. The bank needs a fresh request supported by realistic projections, past performance and clean account conduct.
Apply for the enhancement before your account becomes irregular, and keep your stock statements, GST returns and project figures consistent. If you are also taking a term loan for the expansion, consider presenting both needs together.
A realistic, CA-certified project report with accurate CMA data helps the bank understand your growth and your working capital gap. If you need help with an enhancement proposal or documentation, call or message our team directly. Contact us: +91 89899 77769
FAQs
1. Does the CC limit increase automatically when my business grows?
No. The limit remains the same until the bank sanctions a higher one. You must apply for an enhancement with updated projections, stock statements and financial documents, and the bank will assess it afresh.
2. How do I apply for an enhancement of my cash credit limit?
Submit a written request to your branch with updated CMA data, financials, GST returns, stock statements and the reason for growth. The bank will review your account conduct and decide whether to enhance the limit.
3. What happens if I use more than my Cash Credit limit?
The account becomes irregular. The bank may charge extra, ask you to regularise it, or review the facility. Repeated overdrawing also reduces your chances of getting an enhancement, so apply before you run short.
4. Can I use my cash credit limit to buy machinery for expansion?
No. A Cash Credit limit is for working capital needs such as raw material and stock. Machinery should be financed through a term loan. Using CC for long-term assets can be treated as a diversion of funds.
5. Will the bank ask for extra security for a higher limit?
Possibly. A higher limit increases the bank’s exposure, so it may ask for a larger charge on current assets, additional collateral or revised guarantees. This depends on the bank’s policy and the size of the enhancement.
6. Should I apply for the enhancement and term loan together?
Often it is better. A combined proposal lets the bank assess the machinery and working capital together and keeps your figures consistent. Ask your branch whether it prefers one combined request or separate ones.
7. Does the bank check my past account conduct?
Yes. A regular account with good turnover through the bank helps. If the account has had irregularities or cheque returns, the bank may reduce the enhancement or ask for conditions before approving.
8. How long does an enhancement take?
There is no fixed time. It depends on the bank, the size of the request and how complete your documents are. Clean, consistent paperwork helps the process move faster.