Quick answer: If the GST department cancels your registration, you can get it restored by filing an application for revocation in Form GST REG-21 on the GST portal within 30 days of the cancellation order. This period can be extended by up to 30 days by the Additional or Joint Commissioner and by a further 30 days by the Commissioner. Before applying, you must file all pending returns and pay the tax, interest and late fee due.
At Sharda Associates, our team of Chartered Accountants (CA) handles GST revocation, show cause notice replies, pending return filing and appeals, and also prepares CA-certified project reports for bank loans and business funding. If your GSTIN has been cancelled, the right steps taken at the right time can save your business, your input tax credit and your customers’ trust.
Why Does the Department Cancel GST Registration?
The proper officer can cancel a registration on his own motion under Section 29(2) of the CGST Act, 2017 and Rule 21 of the CGST Rules. Before cancellation, the officer must issue a show cause notice in Form GST REG-17. You get seven working days to reply in Form GST REG-18. If the officer is not satisfied, the cancellation order follows in Form GST REG-19.
The most common reasons are:
- not filing returns for six continuous months (three consecutive tax periods for composition dealers);
- business not found at the registered place of business;
- issuing invoices or bills without actual supply of goods or services;
- wrongly availing or utilizing input tax credit;
- registration obtained by fraud, wilful misstatement or suppression of facts;
- voluntarily registered person not starting business within six months of registration.
Cancellation Scenarios at a Glance
| Reason for cancellation | Legal basis | How to restore |
| Non-filing of returns (6 months, or 3 tax periods for composition) | Section 29(2) | File all pending returns with tax, interest and late fee, then apply in Form REG-21 |
| Business not found at declared address | Rule 21 | Submit rent agreement, electricity bill and photographs of the premises with the revocation application |
| Invoices issued without supply, or ITC violation | Rule 21 | Reply with purchase and sale records, e-way bills and bank proofs; reverse any wrong ITC |
| Registration obtained by fraud or misstatement | Section 29(2) | Very difficult. Seek professional help for a detailed reply and appeal |
| No business started within 6 months (voluntary registration) | Section 29(2) | Apply for revocation if business has begun, otherwise take fresh registration |
What Happens When Your GST Registration Is Cancelled?
Cancellation is not just a paperwork issue. It affects daily business in several ways:
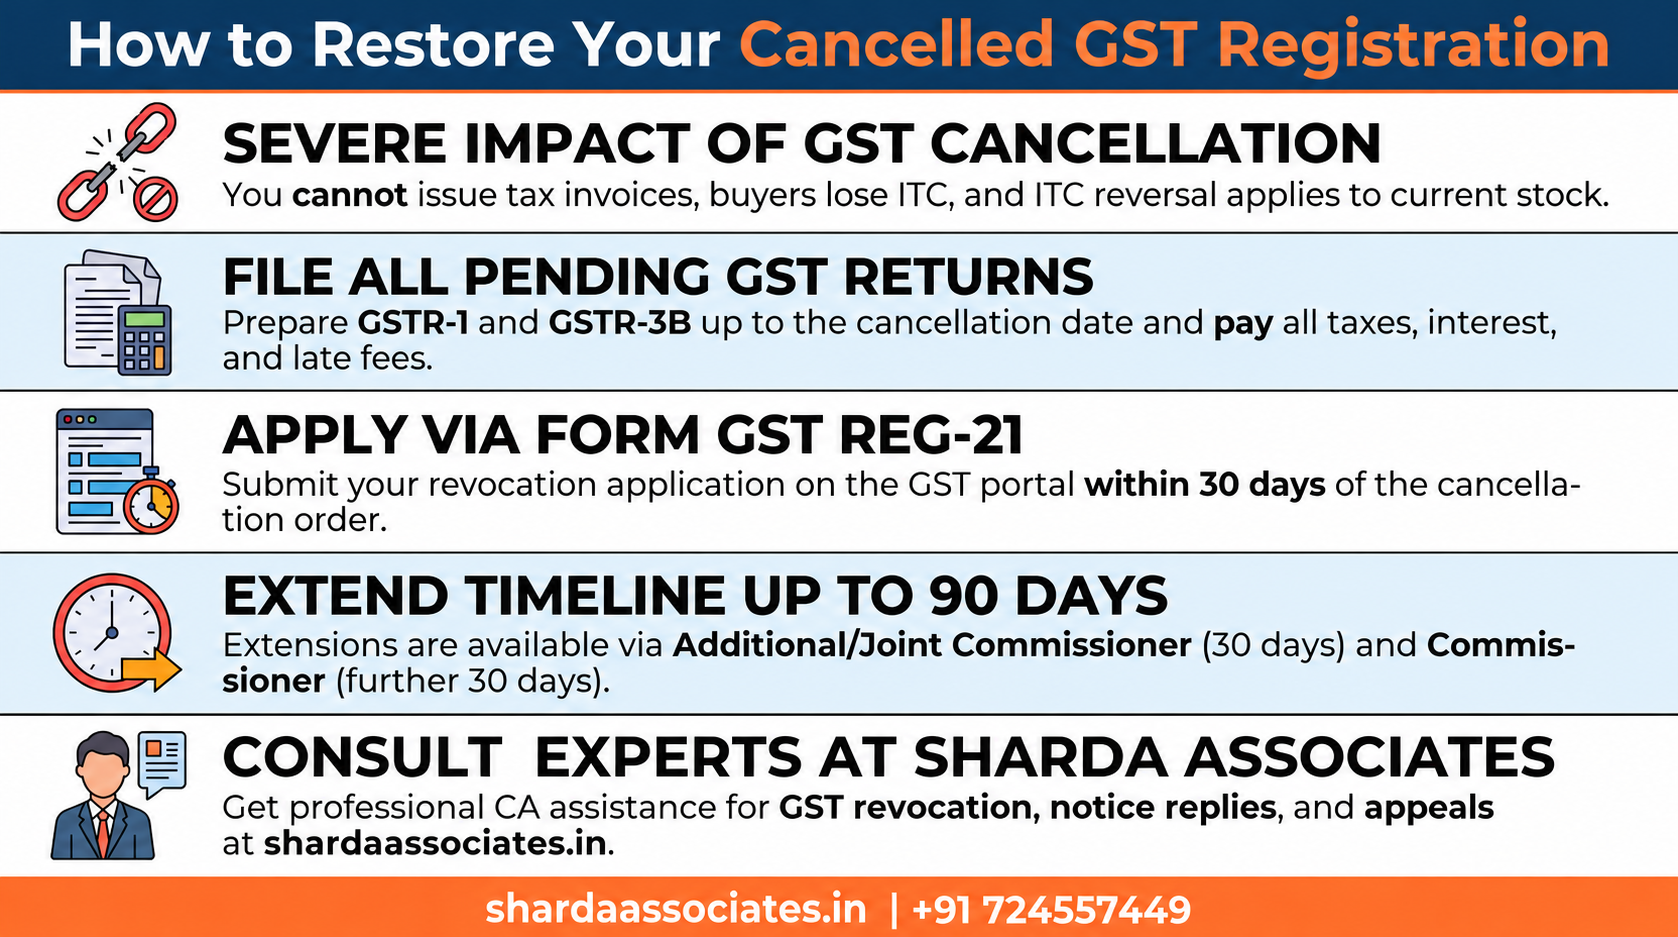
- You cannot issue tax invoices or collect GST from customers from the date of cancellation.
- Your buyers lose ITC on supplies made after cancellation, which may push them to stop dealing with you.
- ITC reversal under Section 29(5) applies on stock, semi-finished goods and capital goods held on the date of cancellation.
- Tender, e-commerce and bank dealings can stop, because a valid GSTIN is needed for most business contracts and loan assessments.
- Pending liabilities remain. Cancellation does not wipe out tax, interest or penalty due for earlier periods.
How to Restore Cancelled GST Registration: Step by Step
- Check the cancellation order. Download Form REG-19 from the GST portal and note the date of the order and the reason given. The limitation period for revocation runs from the date the order was served.
- File all pending returns. Prepare and file every pending GSTR-1 and GSTR-3B up to the date of cancellation, and pay the tax, interest and late fee. Revocation applications without compliance are usually rejected.
- Log in to the GST portal. Go to Services, then Registration, then Application for Revocation of Cancelled Registration, and select Form GST REG-21.
- State the reasons and attach documents. Explain clearly why the default happened and what you have done to cure it. Attach supporting documents such as address proof, bank statements and filed return details.
- Respond to any notice. If the officer is not satisfied, a show cause notice in Form GST REG-23 may be issued. Reply within seven working days with proper evidence.
- Receive the order. The officer must pass an order within 30 days of the application. Revocation is granted in Form GST REG-22, and rejection is communicated in Form GST REG-05.
- Restart compliance. Once your GSTIN is active again, file future returns on time and confirm that your e-way bill and e-invoice access are working.
What If the Time Limit for Revocation Has Expired?
If the revocation period, including the extensions allowed by the Commissioner, is over, you still have options:
- File an appeal before the Appellate Authority under Section 107 against the cancellation order, generally within three months, which can be extended by one month on sufficient cause.
- Approach the High Court through a writ petition if the cancellation was arbitrary, without a proper notice or without reasons. Several High Courts have given relief in genuine cases.
- Take a fresh registration as a last option, keeping in mind that old liabilities and credits stay with the earlier GSTIN. Past one-time amnesty windows for revocation have closed, so check the latest notifications before relying on them.
Documents Usually Needed for Revocation
- cancellation order (REG-19) and show cause notice (REG-17), if any
- proof of principal place of business, such as rent agreement or ownership papers and a utility bill
- filed GSTR-1 and GSTR-3B for all pending periods, with payment challans
- bank statements, purchase and sales invoices and e-way bills
- reply or explanation letter with the reason for default
- authorisation letter or Aadhaar details of the proprietor, partner or director
How to Avoid GST Cancellation in the Future
- File GSTR-1 and GSTR-3B every month or quarter on time, even for nil returns.
- Keep the registered address and contact details updated on the portal.
- Reply to every notice within the time limit, and check the portal and registered email regularly.
- Avoid invoices without genuine supply and check ITC against GSTR-2B before claiming.
- Hire a professional to track due dates and reconcile books every month.
A cancelled GSTIN can also slow down your next loan or expansion plan. Banks usually check GST compliance while reviewing a project report, so Sharda Associates prepares project reports together with GST compliance support, so that your numbers, returns and funding application tell one consistent story.
Conclusion
Cancellation of GST registration by the department is serious, but it is often reversible if you act quickly. Check the order date, file all pending returns, make a well-documented revocation application in Form GST REG-21 and follow up on every notice. If the time limit has passed, an appeal or a writ petition may still help.
For GST registration revocation, notice replies, appeals and CA-certified project reports, contact Sharda Associates at +91-8989977769.
Frequently Asked Questions (FAQs)
1. Can cancelled GST registration be restored?
Yes. You can apply for revocation in Form GST REG-21 within 30 days of the cancellation order, subject to the extensions allowed under Section 30 of the CGST Act.
2. What is the time limit to file a revocation application?
The basic limit is 30 days from the date the cancellation order was served. The Additional or Joint Commissioner can extend it by up to 30 days, and the Commissioner by a further 30 days.
3. Do I need to file pending returns before applying for revocation?
Yes. You should file all pending returns up to the date of cancellation and pay the tax, interest and late fee. Without this, the officer is likely to reject the application.
4. How long does the department take to decide a revocation application?
The officer must pass an order within 30 days of receiving the application, either revoking the cancellation in Form GST REG-22 or rejecting it in Form GST REG-05.
5. What if my revocation application is rejected?
You can file an appeal before the Appellate Authority under Section 107 within the prescribed time, and in suitable cases you can also approach the High Court.
6. Can I issue GST invoices after my registration is cancelled?
No. You cannot collect GST or issue tax invoices while the registration stays cancelled. Doing so can lead to penalties.
7. What happens to my ITC after cancellation?
Under Section 29(5), you must reverse ITC on stock, semi-finished goods and capital goods held on the date of cancellation, or pay the amount prescribed in the rules.
8. Is it better to restore the old GSTIN or take a new registration?
Restoring the old GSTIN is usually better, because it keeps your compliance history, ITC records and customer relationships intact. A fresh registration is mainly a fallback when revocation and appeal are not possible.