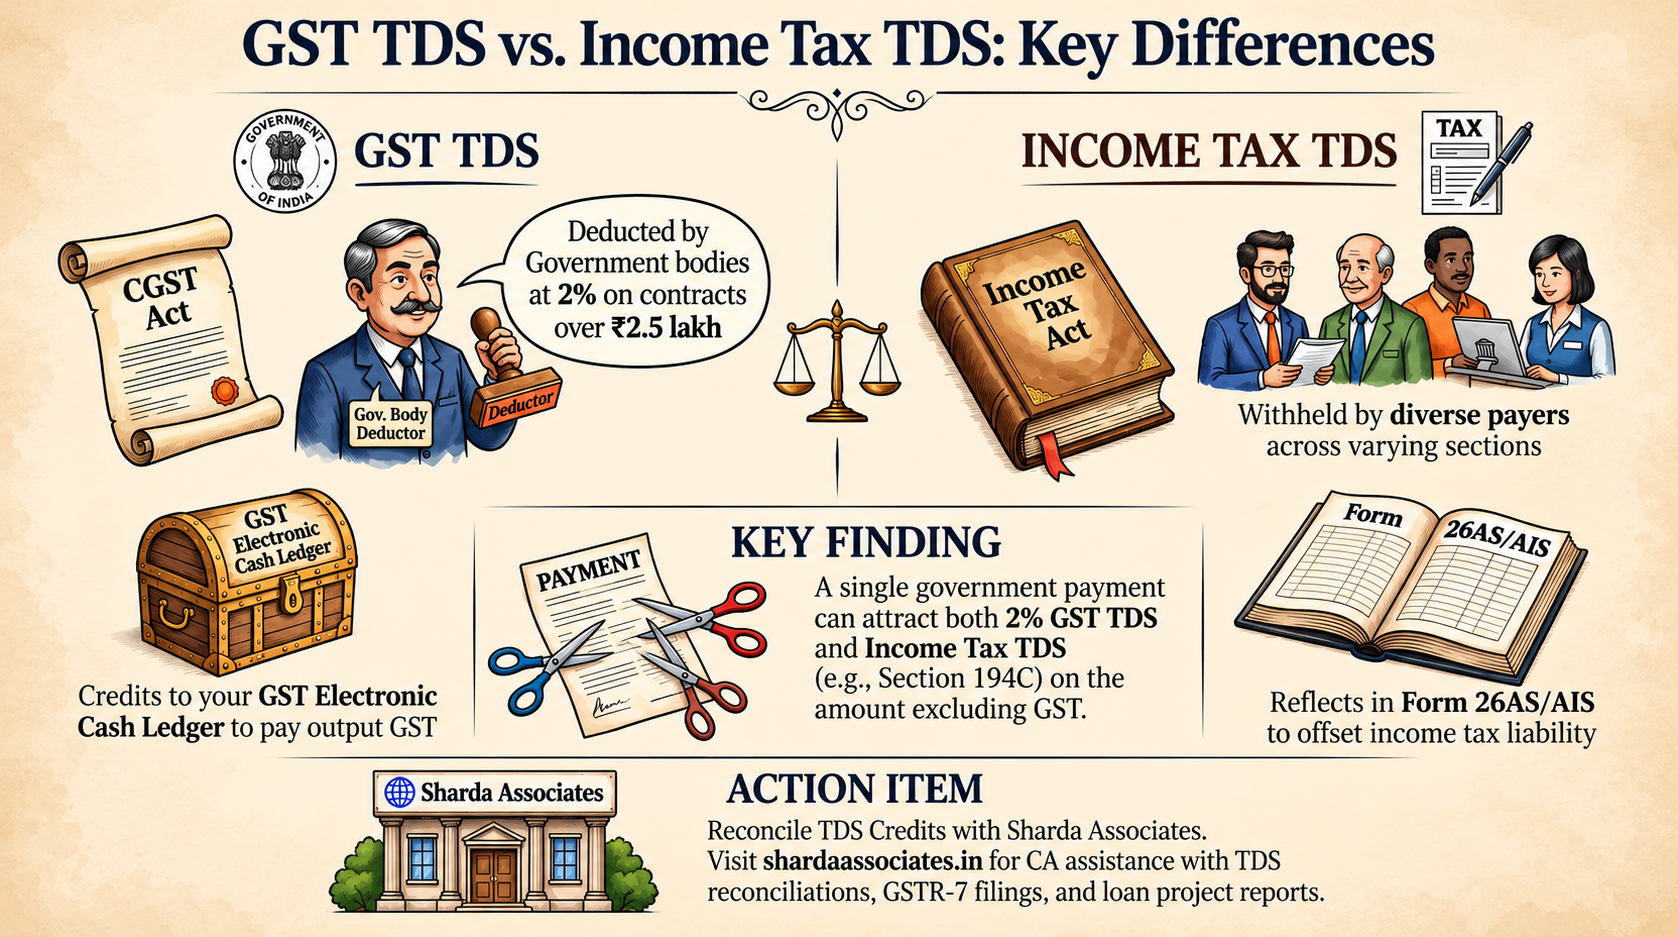
Short answer: GST TDS is tax deducted at source under Section 51 of the CGST Act by government bodies and notified persons, at 2% on contracts above ₹2.5 lakh, and it is credited to the supplier’s GST cash ledger. Income tax TDS is deducted under the Income Tax Act by almost any payer on specified payments, at rates that depend on the section, and it is credited to the payee’s income tax account.
If you supply goods or services to a government office, you may see two different deductions on the same payment advice, and many business owners assume they are one and the same. They are not. Each has its own law, its own deductor, its own return and its own place where you claim credit.
GST TDS vs Income Tax TDS at a Glance
Point | GST TDS | Income Tax TDS |
Law | Section 51, CGST Act, 2017 | Income Tax Act, 1961 (sections such as 192, 194C, 194J) |
Who deducts | Government departments, local authorities, government agencies and notified persons | Any person making specified payments, such as employers, companies and firms |
Payments covered | Taxable supplies of goods or services under a contract above ₹2.5 lakh | Salary, interest, rent, contractor and professional fees, commission and more |
Rate | 2% (1% CGST + 1% SGST, or 2% IGST) | Varies by section, such as 1%, 2%, 5% or 10% |
Threshold | Contract value above ₹2.5 lakh | Different for each section |
Registration | Form GST REG-07 | TAN |
Return | GSTR-7, monthly | Forms 24Q, 26Q, 27Q and others, quarterly |
Due date | 10th of the next month | Deposit by the 7th of the next month, returns by quarterly dates |
Certificate | Form GSTR-7A | Form 16 or Form 16A |
Where the receiver sees it | Electronic cash ledger on the GST portal | Form 26AS and the Annual Information Statement |
How the credit is used | To pay GST liability | To set off income tax, or claim a refund in the ITR |
What Is GST TDS?
GST TDS is a deduction of 2% from payments made by specified government deductors to suppliers of taxable goods or services, when the contract value exceeds ₹2.5 lakh. The deductor files GSTR-7 and deposits the tax by the 10th of the following month. The supplier uses the amount to pay GST liability. Only notified deductors do this, so most businesses never deduct it.
What Is Income Tax TDS?
Income tax TDS is tax withheld at the time of making certain payments, such as salary, interest, rent, contractor charges or professional fees. The payer deposits it with the government and files a quarterly TDS return, and the payee claims credit for it when filing the income tax return. It applies to a far wider set of payers than GST TDS, including companies, firms and individuals who are covered by the relevant section.
Can Both Apply on the Same Payment?
Yes, when a government deductor pays a contractor. Take an invoice of ₹10,00,000 plus 18% GST, so the bill is ₹11,80,000.
- GST TDS at 2% is ₹20,000, calculated on the value excluding GST.
- Income tax TDS under Section 194C for a company contractor at 2% is another ₹20,000, also calculated on the amount excluding GST where the GST is shown separately.
- The supplier receives ₹11,80,000 minus ₹40,000, which is ₹11,40,000.
Each deduction is reported and credited separately, and the rates vary with the section and the status of the payee (for example, Section 194C is 1% for an individual or HUF contractor).
Which Credit Do You Get and Where?
GST TDS goes to your electronic cash ledger on the GST portal, and you use it to pay output GST. Income tax TDS appears in Form 26AS and AIS, and you claim it in your income tax return, where it reduces your tax or comes back as a refund. The two credits cannot be swapped, so track both separately.
How We Help
At Sharda Associates, our Chartered Accountants (CA) reconcile both kinds of TDS for suppliers who bill government departments, and help deductors register, deduct and file correctly. We also prepare CA-certified project reports for bank loans, where unreleased TDS credits and receivables from government clients are checked closely.
Questions People Ask
Q1. Is GST TDS the same as income tax TDS?
No. They are under different laws and have different deductors, rates, returns and credits.
Q2. Who deducts GST TDS?
Government departments, local authorities, government agencies and notified persons such as certain public sector bodies.
Q3. What is the rate of GST TDS?
2% of the payment value excluding GST.
Q4. Is there a limit for GST TDS?
Yes. It applies when the contract value exceeds ₹2.5 lakh.
Q5. Does income tax TDS have one rate?
No. The rate depends on the section and the nature of the payment.
Q6. Can a payment attract both TDS?
Yes. A government payment to a contractor can attract both GST TDS and income tax TDS.
Q7. Is TDS under income tax calculated on the amount including GST?
If GST is shown separately in the invoice, TDS is generally calculated on the amount excluding GST.
Q8. Which return is filed for GST TDS?
GSTR-7, every month.
Q9. Which form shows income tax TDS to the payee?
Form 26AS and the Annual Information Statement.
Q10. Can GST TDS credit be used against income tax?
No. It can be used only to pay GST liability.