Understanding Section 43B(h) of the Income Tax Act and Clause 22 of Form 3CD is essential for businesses purchasing goods or services from micro and small enterprises. Sharda Associates provides professional tax audit services, accounting and bookkeeping, and MSME payment compliance support to help businesses maintain accurate financial records and meet applicable tax requirements.
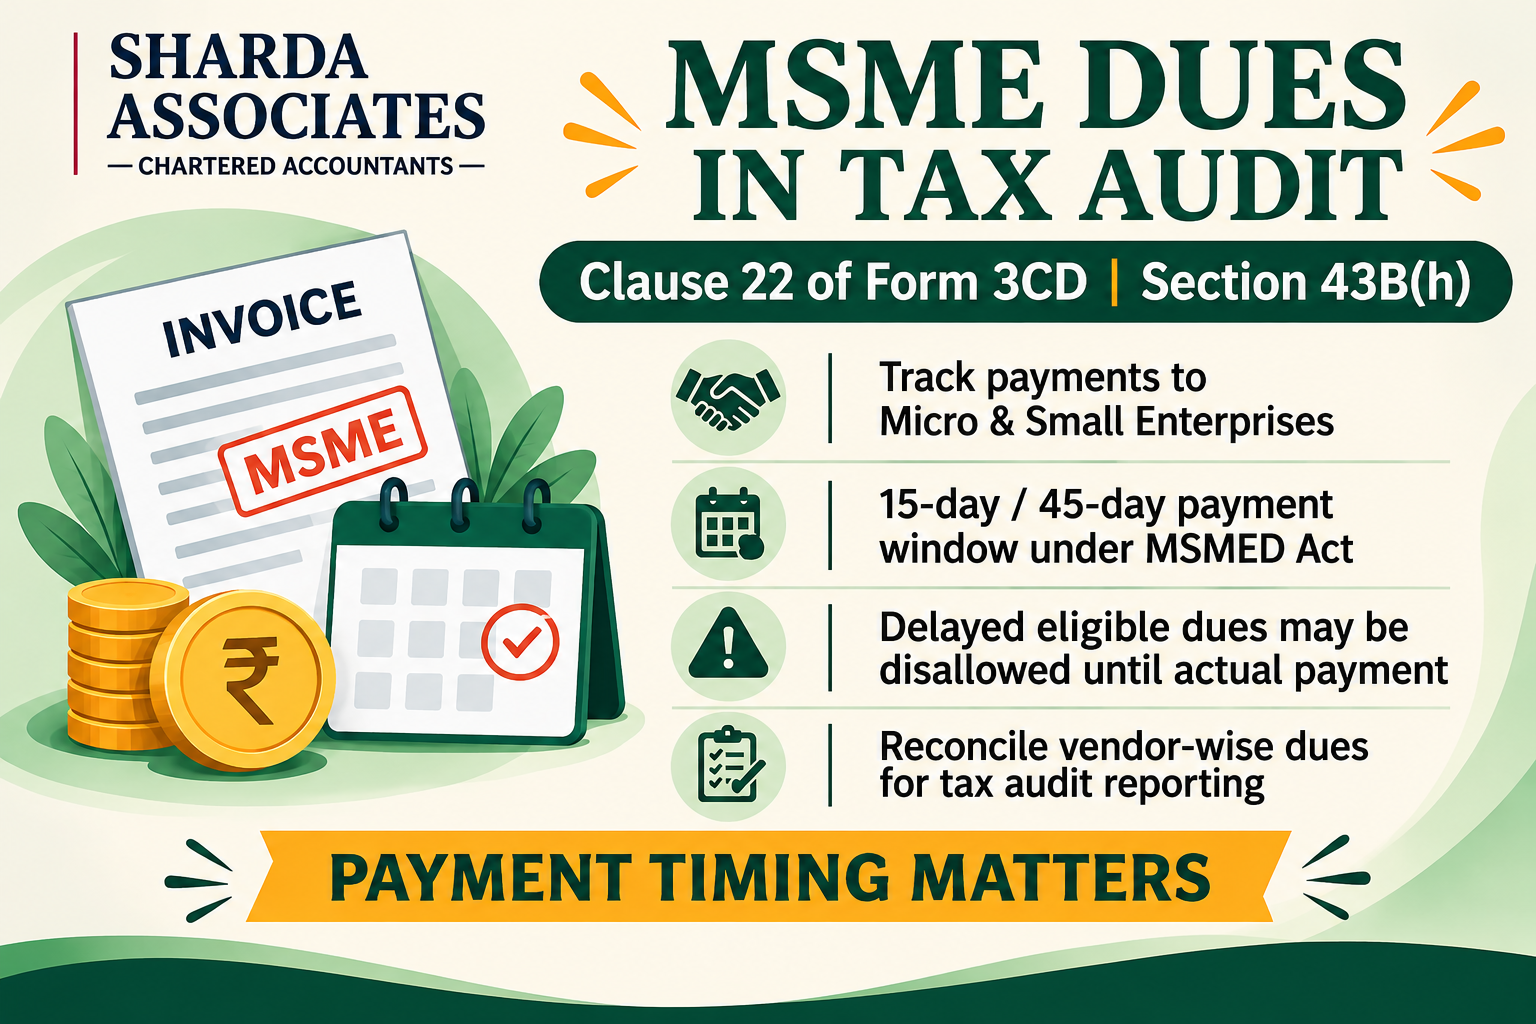
Under Section 43B(h), payments due to eligible micro and small enterprises must generally be made within the time limit prescribed under Section 15 of the MSMED Act. If payment is delayed beyond the permitted period, the related business expense may be disallowed until it is actually paid. Clause 22 of Form 3CD requires tax auditors to report relevant outstanding amounts and payment details.
This guide explains the MSME payment rules, tax audit reporting requirements, applicable deadlines and common mistakes businesses should avoid.
This guide explains the rule, the Clause 22 disclosure, the 15 and 45 day limit, and a simple checklist.
Quick Answer: Section 43B(h) says that payments to micro and small enterprise suppliers are deductible only in the year you actually pay, and only if paid within the time allowed by the MSMED Act: 15 days with no written agreement, or the agreed period capped at 45 days. Clause 22 of Form 3CD makes the tax auditor report the interest due to MSME suppliers, the total payable to them, and how much was paid within or beyond the limit. Unpaid amounts after the due period are added back to your income for that year and allowed only in the year you pay them.
Four rules at a glance
| Rule | What it does |
| Section 43B(h), Income-tax | Allows the expense only when paid, for MSME dues beyond the limit |
| Clause 22, Form 3CD | Requires the auditor to report MSME dues and interest |
| Section 15, MSMED Act | Sets the 15 and 45 day payment period |
| Form MSME-1 | Half-yearly return of dues outstanding for over 45 days, filed with the ROC |
The Income-tax Act, 2025 applies from 1 April 2026. Check the renumbered section and the revised form before you quote these rules for FY 2026-27.
What is Section 43B(h)?
It was introduced by the Finance Act, 2023. Unlike other items in Section 43B, paying by the return due date does not save the deduction here. If the amount stays unpaid beyond the permitted period at the year end, you add it back to your income. You get the deduction in the year you pay.
How long can you take to pay?
- No written agreement: 15 days from the day of acceptance or deemed acceptance of goods or services.
- Written agreement: the agreed period, but never more than 45 days.
The clock starts at acceptance, not the invoice date. Keep your delivery and acceptance records safe. Our guide to organising billing and payment records will help.
What does Clause 22 of Form 3CD ask?
From 1 April 2025, Clause 22 has three parts:
- The interest inadmissible under Section 23 of the MSMED Act.
- The total amount payable to micro and small enterprises during the year.
- The split between amounts paid within the permitted period and amounts that fall outside it.
Your auditor needs supplier-wise ledgers, the Udyam status of each supplier and the payment dates. Keeping this data ready is a job for strong accounting and bookkeeping.
Who is covered?
- Micro and small enterprise suppliers that are registered on Udyam and provide goods or services.
- Medium enterprises and traders are generally outside Section 43B(h).
- Size limits were revised from 1 April 2025: micro up to ₹2.5 crore investment and ₹10 crore turnover, small up to ₹25 crore investment and ₹100 crore turnover.
Ask each supplier for the Udyam certificate and keep a copy.
A worked example
| Invoice | Amount | Paid in | Treatment |
| A | ₹5,00,000 | Within 45 days | Allowed |
| B | ₹4,00,000 | Within 45 days | Allowed |
| C | ₹6,00,000 | Not paid beyond limit at year end | Added back |
| D | ₹3,00,000 | Not paid beyond limit at year end | Added back |
Out of ₹18 lakh, ₹9 lakh is added back to income. At a 25% rate, the extra tax is about ₹2.25 lakh plus cess, and you get the deduction back only when you pay.
The cost of delay
- Disallowance of the expense for the year.
- Interest to the supplier at three times the RBI Bank Rate, compounded monthly, and this interest is not deductible.
- Advance tax and penalty exposure on the extra income.
- Form MSME-1 defaults and questions from your auditor.
For suppliers, late payment hurts cash flow. If you are an MSME waiting for money, read our guide on invoice discounting vs business loans and the CGTMSE scheme.
A 6-step checklist for FY 2026-27
- List all suppliers and tag them micro, small or others using Udyam.
- Record the acceptance date for each invoice.
- Check payment terms and any written agreements.
- Review the ageing every month, and pay before day 45.
- Clear overdue MSME dues before 31 March 2027.
- Give your auditor a supplier-wise statement for Clause 22.
If you need working capital to pay on time, a CMA report for bank loan and a project finance consultant can arrange it.
Conclusion
Timely payments to micro and small enterprise suppliers are not just good business practices; they are also important for income tax compliance. Under Section 43B(h), delayed payments beyond the prescribed period may result in expenses being disallowed until the actual payment is made. This can increase your taxable business income and affect tax planning.
Business owners should review supplier ageing reports regularly, clear outstanding MSME dues within applicable timelines and maintain accurate payment records. Proper documentation also helps prepare the MSME Clause 22 reporting in Form 3CD and simplifies tax audits.
Need assistance with MSME payment compliance, income tax audits or accounting records? Contact Sharda Associates at +91 79870 21896 or +91 89899 77769, or contact our team online for professional guidance.
Frequently asked questions
1. What is Section 43B(h)?
A rule that allows a deduction for dues to micro and small suppliers only when they are actually paid within the permitted time.
2. What is the payment limit?
15 days without a written agreement, or the agreed period capped at 45 days.
3. Does paying before the return due date save the deduction?
No. For this clause, you must pay within the permitted period, or the deduction comes only in the year of payment.
4. Are medium enterprises and traders covered?
Generally no. The rule is aimed at micro and small suppliers registered on Udyam.
5. What does Clause 22 of Form 3CD require?
Reporting of interest under the MSMED Act, total payable to MSEs and the split between timely and delayed amounts.
6. What interest applies on delayed MSME payment?
Three times the RBI Bank Rate, compounded monthly, and it is not an allowable expense.
7. What happens to the amount added back?
It is allowed in the year you pay it.
8. Does every business need to worry about this?
Any business buying from micro or small suppliers on the mercantile basis should track it, whether or not it is audited.