Sharda Associates is a chartered accountant business and financial consultancy firm that has prepared over 45,500 CA-certified project reports. In addition to project report preparation, the firm provides professional assistance with income tax return filing, tax audit compliance, company and LLP taxation, financial documentation, and income tax notices. Sharda Associates helps businesses and taxpayers understand CBDT notifications, determine their applicable filing deadlines, and complete their tax compliance requirements accurately.
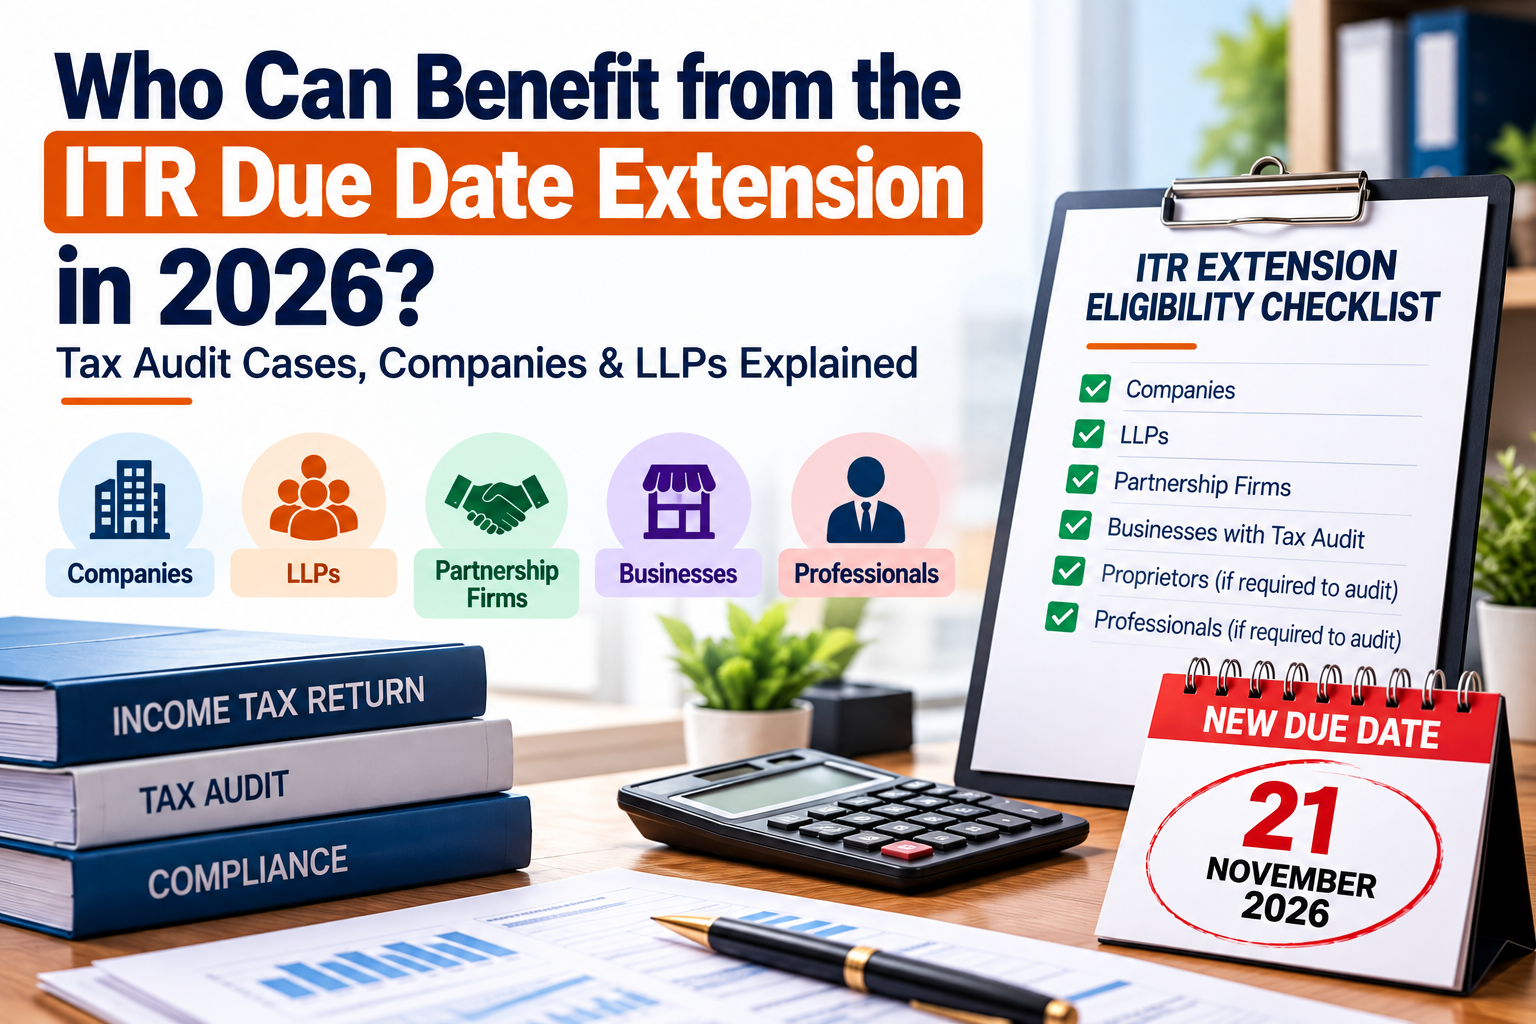
Quick Answer: The Central Board of Direct Taxes (CBDT) has extended the Income Tax Return filing deadline for Assessment Year 2026-27 to 21 November 2026 for taxpayers covered under the specified audit-related category of Section 139(1) of the Income-tax Act, 1961. Companies, LLPs, partnership firms and business owners may qualify depending on their applicable statutory requirements. This extension does not automatically apply to every taxpayer.
Many taxpayers are confused about whether the revised ITR deadline applies to their business. For example, does every private limited company qualify? Can an LLP file its return by 21 November? What if a proprietor is not required to undergo a tax audit?
Understanding these differences is important before deciding your filing deadline.
Need help checking your ITR due date eligibility? Sharda Associates can assist companies, LLPs, partnership firms, business owners, and professionals in identifying their applicable filing deadlines, reviewing tax documents, and completing income tax return filing requirements.
Contact Sharda Associates: +91 89899 77769
What Is the ITR Due Date Extension
The Central Board of Direct Taxes (CBDT), through Circular No. 07/2026 dated 28 September 2026, extended the ITR filing deadline for specified taxpayers.
The revised dates are:
| Particulars | Previous Deadline | Extended Deadline |
| ITR Filing for Eligible Audit Cases | 31 October 2026 | 21 November 2026 |
| Relevant Tax Audit Report | 30 September 2026 | 21 October 2026 |
The extension relates to Financial Year 2025-26 and Assessment Year 2026-27.
Importantly, the revised ITR deadline is not a general extension for all taxpayers.
Are Private Limited Companies Eligible for the Extension?
Generally, yes.
Companies normally fall within the audit-related filing category under Section 139(1), subject to the applicable statutory provisions.
Therefore, a private limited company covered by this category may use the extended deadline of 21 November 2026.
However, companies required to furnish a transfer pricing report under Section 92E fall within a separate filing category.
Businesses should verify their specific return-filing requirements rather than assume that every company has the same deadline.
Does the Extension Apply to LLPs?
Yes, but eligibility depends on the LLP’s audit requirements.
An LLP whose accounts are required to be audited under the Income-tax Act or another applicable law may fall within the specified category.
However, merely being registered as an LLP does not automatically establish eligibility for this extension.
For example:
Example A: An LLP whose accounts are required to be audited under the applicable provisions may qualify for the extended deadline.
Example B: An LLP not subject to the relevant audit requirements should verify its separate statutory ITR due date.
LLPs should also ensure that their financial statements and relevant audit reports are correctly prepared.
Can Proprietorship Businesses Use the Extended Deadline?
A proprietorship business may qualify if its accounts are required to be audited under the applicable provisions.
The business structure alone does not determine eligibility.
For example, a proprietor whose business is subject to tax audit under Section 44AB may fall within the eligible category.
However, a small business owner who is not subject to the relevant audit requirements cannot automatically claim the 21 November deadline.
Therefore, proprietors should review their turnover, applicable audit provisions and filing category before relying on the extension.
Are Partnership Firms Covered by the Extension?
Partnership firms may also qualify where the relevant audit requirements apply.
The extension can additionally affect certain partners whose filing deadlines are linked to the audit requirement of the firm, as provided under Section 139(1).
However, eligibility must be evaluated according to the statutory provisions applicable to the firm and its partners.
A partnership firm that is not covered by the specified audit-related category should follow its independently applicable filing deadline.
Who Is Not Automatically Eligible?
The extension does not automatically cover:
- Salaried individuals without applicable audit requirements.
- Pensioners filing ordinary individual returns.
- Non-audit proprietorship businesses.
- Non-audit professionals.
- Other taxpayers outside the specified category.
Taxpayers should also distinguish between the extended ITR filing deadline and the separate due date applicable to transfer pricing cases.
Important: Filing deadlines depend on the taxpayer’s legal category and statutory requirements, not merely their business name or entity type.
How Can You Check Whether You Qualify?
Before filing your ITR, follow these steps:
Step 1: Identify whether you are filing as an individual, company, LLP, partnership firm or another entity.
Step 2: Verify whether your accounts are required to be audited under the Income-tax Act or another applicable law.
Step 3: Check whether Section 92E transfer pricing reporting requirements apply.
Step 4: Review the filing category under Section 139(1).
Step 5: Confirm the relevant CBDT circular and applicable due date.
Step 6: Prepare and submit the appropriate return within the statutory timeline.
If your filing category is unclear, professional review can help avoid incorrect assumptions.
What Happens If an Eligible Taxpayer Misses the Deadline?
Missing the applicable ITR filing deadline may result in consequences under the Income-tax Act.
Depending on the facts, these can include:
- Late filing fees under Section 234F.
- Interest under applicable provisions.
- Restrictions on carrying forward certain business or capital losses.
- Additional compliance requirements.
Failure to complete a required tax audit report within its applicable deadline may also have separate consequences.
The extension of an ITR filing deadline does not automatically eliminate earlier compliance failures.
Conclusion
The ITR due date extension to 21 November 2026 is an important compliance update for eligible taxpayers for AY 2026-27.
However, eligibility depends on the applicable statutory provisions, audit requirements and taxpayer category.
Companies, LLPs, partnership firms and business owners should confirm their filing status instead of assuming that the revised deadline applies universally.
Phone: +91 89899 77769
Frequently Asked Questions
Q1. What is the new ITR deadline for eligible audit cases in 2026?
The revised deadline is 21 November 2026 for the specified category covered by CBDT Circular No. 07/2026.
Q2. Can every LLP file its ITR by 21 November 2026?
No. An LLP must satisfy the applicable audit-related eligibility requirements.
Q3. Are private limited companies eligible?
Generally, companies covered by the specified filing category qualify, subject to applicable exceptions.
Q4. Does the extension apply to non-audit businesses?
Not automatically. Non-audit taxpayers must follow their own applicable deadlines.
Q5. Has the tax audit report deadline also changed?
Yes. The relevant tax audit report deadline was extended to 21 October 2026.
Q6. Does the extension apply to transfer pricing cases?
Not automatically. Taxpayers covered by Section 92E generally have a separate statutory filing category.