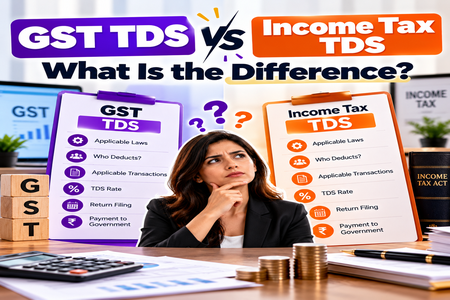
Short answer: GST TDS is tax deducted at source under Section 51 of the CGST Act by government bodies and notified persons, at 2% on contracts above ₹2.5 lakh, and it is credited to the supplier’s GST...
The CBDT has extended the tax audit report date for AY 2026-27 from 30 September to 21 October 2026 and the return date for audit cases from 31 October to 21 November 2026. If your accounts are...
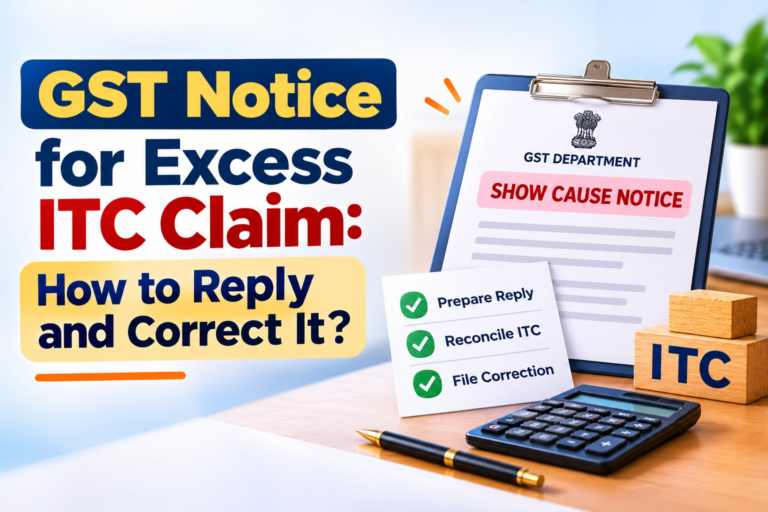
GST Notice for Excess ITC Claim: How to Reply and Correct It Short answer: First identify the form: DRC-01C (intimation, 7 days), ASMT-10 (scrutiny, reply in ASMT-11), or a show cause notice. Then...
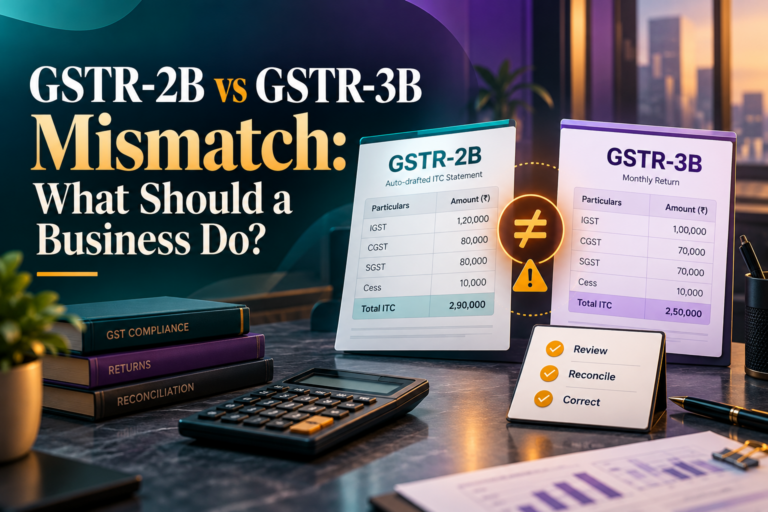
To resolve a GSTR-2B vs GSTR-3B mismatch, reconcile your purchase records with GSTR-2B before filing GSTR-3B each month. Claim Input Tax Credit (ITC) only when it is supported by GSTR-2B and satisfies...
Short answer: No. Only expenses incurred wholly and exclusively for the business are deductible, and personal expenses are excluded. If an item is used partly for business and partly for personal use...
Short answer: For income tax, a business claim expenses even without a GST invoice if it is genuine, incurred wholly and exclusively for the business, and supported by other reliable evidence, with...
Short answer: A current account transactions is not watched in isolation. Banks report certain transactions to the Income Tax Department, such as aggregate cash deposits or withdrawals of ₹50 lakh or...
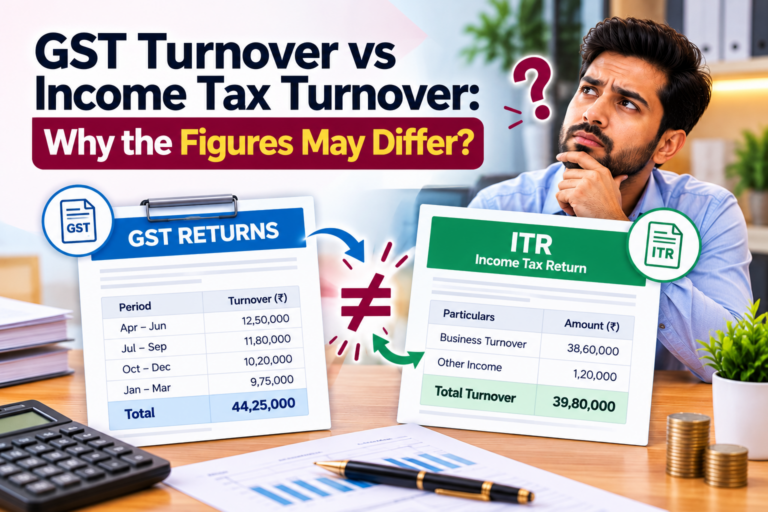
Short answer: GST turnover vs income tax turnover differs because GST turnover is calculated from supplies reported in your GST returns, based on invoices and time-of-supply rules, while income tax...
Short answer: Generally, no, not until the invoice appears in your GSTR-2B. Section 16(2)(aa) allows ITC only when the supplier has furnished the invoice details in GSTR-1 or IFF and they are...