Quick Answer: Yes. If you missed the original ITR filing deadline for Assessment Year (AY) 2026–27, you can generally file a belated Income Tax Return by 31 December 2026, or before completion of assessment, whichever is earlier. However, late filing may attract a fee under Section 234F and interest under Section 234A, depending on your tax liability.
Missing the Income Tax Return (ITR) deadline can create confusion for salaried employees, freelancers, professionals, and business owners. Many taxpayers worry that they cannot file their returns once the original due date has passed. However, the Income Tax Act provides an option to file a belated return within the prescribed time limit.
For Assessment Year 2026–27, the general belated return deadline is 31 December 2026. If you have not filed your return for income earned during FY 2025–26, understanding the applicable late fees, interest, and filing procedure can help you avoid further complications.
Can You File ITR After the Original Due Date?
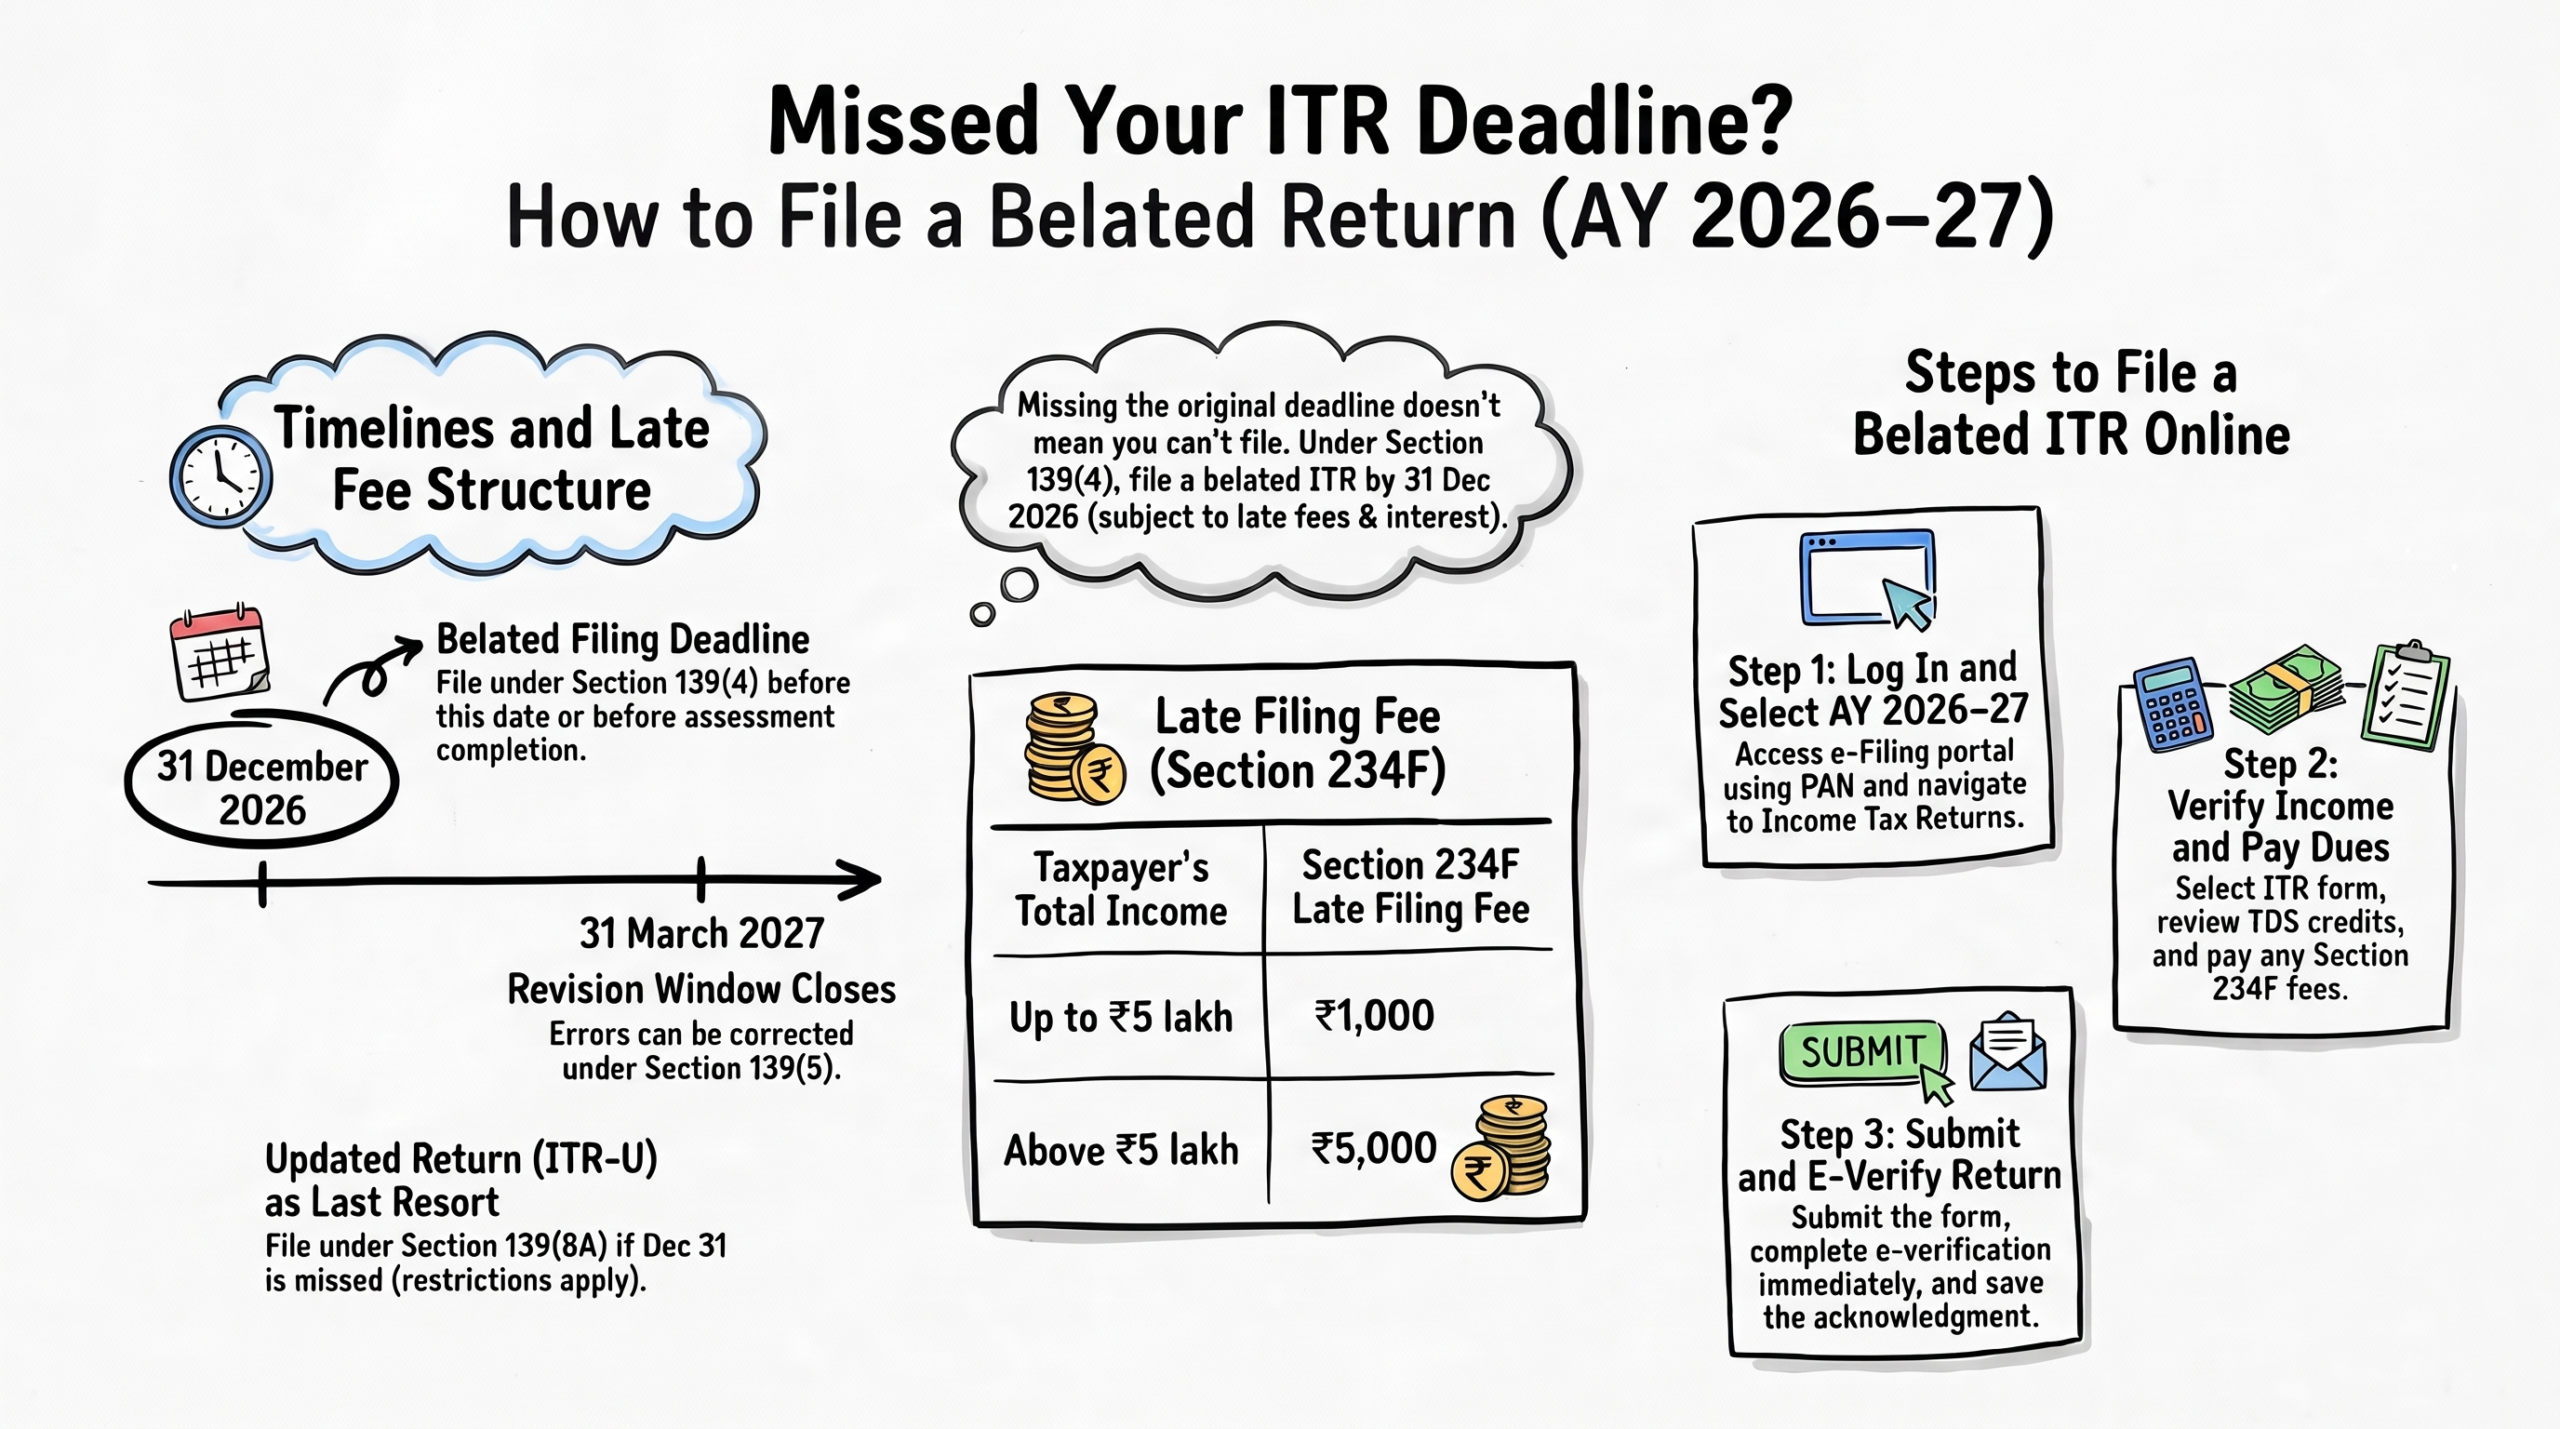
Yes. Under Section 139(4) of the Income-tax Act, 1961, taxpayers who miss their original filing deadline can generally submit a belated return before 31 December 2026 for AY 2026–27, or before completion of assessment, whichever occurs earlier.
A belated return allows taxpayers to report their income, claim eligible tax credits, and complete their pending tax compliance. However, certain benefits and loss carry-forward provisions may be restricted when filing late.
What Is the Last Date to File a Belated ITR for AY 2026–27?
The last date for filing a belated return for AY 2026–27 is 31 December 2026, subject to completion of assessment.
The deadline applies to taxpayers who missed their respective original due dates. The original due date depends on the taxpayer’s category, such as individuals, non-audit businesses, and audit cases.
What Happens If You Miss the 31 December 2026 Deadline?
If you also miss the belated return deadline, you generally cannot file a regular belated return under Section 139(4).
Depending on your circumstances, you may be eligible to file an Updated Return (ITR-U) under Section 139(8A). However, an updated return has restrictions and cannot generally be used to declare a loss, reduce tax liability, or claim an additional refund.
An updated return may also involve additional tax payments, so taxpayers should examine eligibility before choosing this option.
What Is the Late Filing Fee for ITR?
Under Section 234F of the Income-tax Act, 1961, the late filing fee is:
| Taxpayer’s total income | Late filing fee |
| Up to ₹5 lakh | ₹1,000 |
| Above ₹5 lakh | ₹5,000 |
The fee applies subject to the provisions governing delayed returns.
Apart from the late filing fee, interest may also apply if tax remains unpaid.
How to File a Belated Income Tax Return Online?
Follow these steps to file your pending ITR:
- Visit the official Income Tax e-Filing portal.
- Log in using your PAN and password.
- Select e-File and then Income Tax Returns.
- Choose File Income Tax Return.
- Select Assessment Year 2026–27.
- Choose the applicable ITR form and filing category.
- Verify your income, deductions, TDS and tax payments.
- Pay any outstanding tax, interest or applicable late filing fee.
- Submit your return and complete e-verification.
Always download and preserve your ITR acknowledgement for future reference.
Can You Revise Your Belated ITR After Filing?
Yes. A belated return can generally be revised under Section 139(5) if you discover an error or omission. For AY 2026–27, the revised return deadline is generally 31 March 2027 or completion of assessment, whichever is earlier, subject to applicable provisions.
This gives taxpayers an opportunity to correct eligible mistakes in their filed returns.
How Sharda Associates Can Help
Filing a belated ITR involves checking income details, TDS credits, deductions, tax liability and applicable late fees. Incorrect information or missed disclosures can create further compliance issues.
Sharda Associates assists individuals, professionals, startups, and business owners with income tax return filing, tax calculations, and income tax compliance.
Conclusion
Missing the original ITR deadline does not necessarily mean you have lost the opportunity to file your return. Eligible taxpayers can generally submit a belated ITR for AY 2026–27 by 31 December 2026, subject to applicable conditions.
Check your income, tax credits, and outstanding liability before filing to avoid unnecessary errors and additional costs. If you need professional assistance, Sharda Associates can help you complete your income tax compliance.
For assistance with your pending ITR or tax filing requirements, contact Sharda Associates: +91 89899 77769 |
Frequently Asked Questions
1. Can I file my ITR after 31 July 2026?
Yes. If you missed your applicable original deadline, you can generally file a belated return by 31 December 2026, subject to completion of assessment.
2. Is 31 December 2026 the last date for belated ITR?
Yes, for AY 2026–27, the general belated return deadline is 31 December 2026 or completion of assessment, whichever is earlier.
3. Can I claim an income tax refund through a belated return?
Yes. Eligible taxpayers can claim a refund through a belated return, subject to applicable filing requirements and restrictions.
4. Will I have to pay a penalty for filing ITR late?
A late filing fee under Section 234F may apply. Interest under Section 234A may also be payable if tax remains outstanding.
5. Can I file ITR without paying the late filing fee?
If a late filing fee is legally applicable, it must be paid before completing the return filing process. Eligible exemptions or specific provisions should be checked.
6. Can salaried employees file belated ITR?
Yes. Salaried employees who miss their applicable original filing deadline can generally file a belated return within the prescribed period.
7. What if I miss the belated ITR deadline too?
You may be able to file an Updated Return (ITR-U) under Section 139(8A), subject to eligibility conditions, additional tax and other statutory restrictions.
8. Can I revise my belated ITR after 31 December 2026?
Generally, yes. For AY 2026–27, a revised return may be filed up to 31 March 2027 or completion of assessment, whichever is earlier, subject to applicable law.