Before submitting a loan application, borrowers should focus on improving the overall quality, accuracy and consistency of their financial file. A lender evaluates the complete picture presented through documents, financial records and repayment capacity. Therefore, the first step should be reviewing all financial records carefully. GST returns should match the accounting records, income shown in the ITR should reflect actual earnings, bank statements should support declared business or income activities, and all existing loans or financial obligations should be properly disclosed.
Borrowers should also prepare realistic financial projections instead of increasing figures only to justify a higher loan amount. Financial estimates should be supported by practical business factors such as production capacity, expected market demand, pricing assumptions, operating expenses and the working capital cycle. A lender generally checks whether the projected revenue and cash flow are achievable based on the actual business model and available resources.
Sharda Associates helps businesses strengthen their loan applications with professional MSME Registration and CA-certified Project Reports designed to present the business clearly to lenders. With 45,500+ reports delivered across India, Sharda Associates provides accurate business documentation starting at ₹2,999, with fast 24–48 hour delivery. A professionally prepared project report can help organise your financial projections, investment requirements, profitability estimates, and repayment planning before you approach the bank.
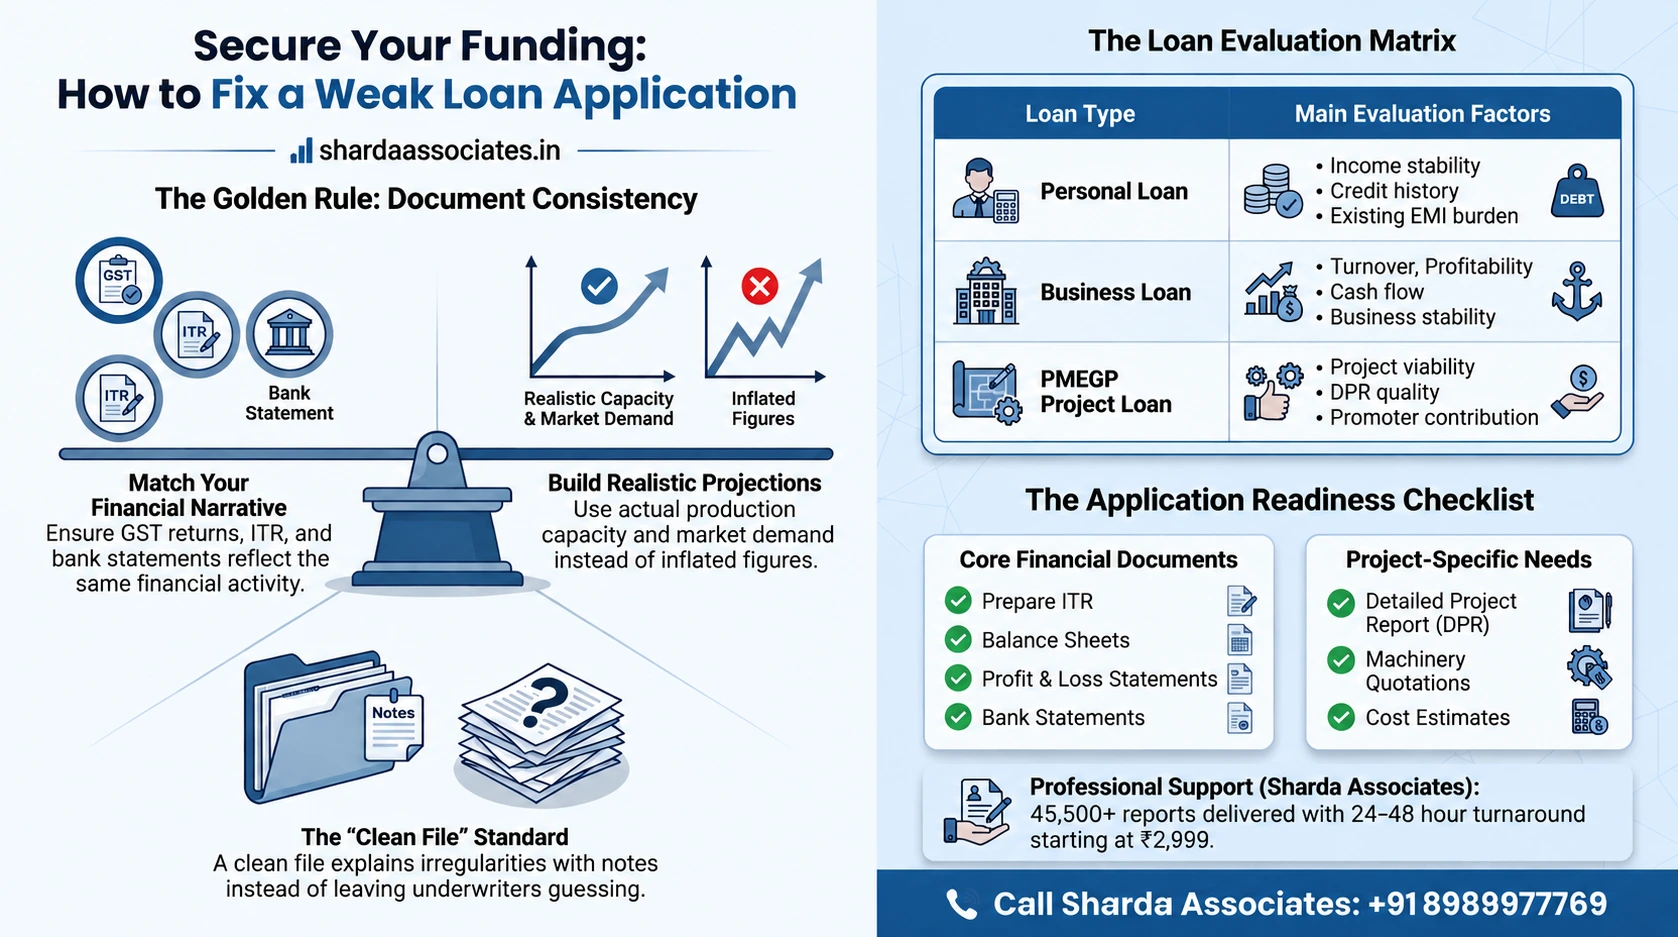
Difference Between Personal Loan, Business Loan & PMEGP Loan Evaluation
Although the basic principle remains the same — repayment ability and credibility — each loan type focuses on different areas.
| Loan Type | Main Evaluation Factors |
| Personal Loan | Income stability, credit history, existing EMI burden, employment profile |
| Business Loan | Turnover, profitability, cash flow, financial statements, business stability |
| PMEGP Project Loan | Project viability, DPR quality, promoter contribution, business activity, eligibility criteria |
Loan Application Checklist
Before applying, keep the following ready:
Personal Documents
✔ PAN Card
✔ Aadhaar/KYC documents
✔ Address proof
✔ Income documents
Business Documents
✔ Business registration documents
✔ GST registration and returns (where applicable)
✔ Udyam Registration (if applicable)
✔ Business licences
Financial Documents
✔ Income Tax Returns
✔ Balance Sheet
✔ Profit & Loss Statement
✔ Bank Statements
✔ Existing loan details
Project Loan Documents
✔ Detailed Project Report
✔ Machinery quotations
✔ Project cost estimates
✔ Working capital calculation
✔ Financial projections
What a Clean File Actually Looks Like
It isn’t a file with a perfect profile — it’s a file where every number, on every document, tells the same story, and where anything unusual has a one-line explanation sitting next to it instead of the silence the underwriter has to chase. This is the same principle whether the application is a personal loan, an MSME term loan, or a scheme-backed project report — the underwriting logic doesn’t change with the loan product, only the specific ratios and thresholds do.
At Sharda Associates, when we prepare a project report, CMA data, or a set of financial statements for a loan application, this cross-consistency check — ITR against GST against bank statements against the report itself — is one of the first things we do, precisely because it’s the gap most applicants don’t think to check themselves.
Conclusion
A weak loan application can reduce your chances of getting timely approval, especially when financial details, business projections, documentation, or repayment plans are incomplete. Before applying, review your financial statements, improve your credit profile, organize the required documents, and prepare a clear Project Report for a bank loan that explains your business and funding requirements.
Sharda Associates can help you prepare professional CA-certified Project Reports, MSME Registration, and loan documentation to present your business requirements more effectively. With 45,500+ reports delivered across India, expert documentation starts at ₹2,999 with 24–48 hour delivery.
📞 Call Sharda Associates: +918989977769 to discuss your project report and loan documentation requirements.
Frequently Asked Questions
Q1. Do the same weak points apply to personal loans and business loans equally?
The specific ratios differ (FOIR for personal loans, DSCR for business loans), but the underlying pattern — consistency across documents, explained irregularities, a request sized to capacity — applies to both.
Q2. If my numbers don’t perfectly match across documents, is that always fraud?
No — most mismatches are genuine inconsistencies in how records were kept, not intentional misrepresentation. But the underwriter can’t tell that from the file alone, so it still triggers scrutiny.
Q3. Does explaining an irregularity actually help, or does it just draw attention to it?
It helps. Underwriters are typically less concerned by an explained irregularity than by an unexplained one — silence reads as something being hidden even when nothing is.
Q4. Is applying to multiple lenders after one rejection a reasonable strategy?
It’s a common instinct, but each application adds a fresh hard enquiry, and several in a short window generally work against the applicant rather than for them.
Q5. Can a loan be rejected even with a good credit score?
Yes. Credit score is only one part of evaluation. Banks also assess repayment capacity, income/business stability and documentation quality.
Q6. Does rejection from one bank affect future loan applications?
The rejection itself is not usually the main issue, but multiple applications and credit enquiries within a short period may affect lender perception.
Q7. Can I apply again after loan rejection?
Yes, but it is better to understand the reason for rejection and improve the weak areas before submitting another application.
Q8. Why is cash flow important even when the business is profitable?
Profit shown in financial statements does not always mean immediate availability of cash for EMI payments.