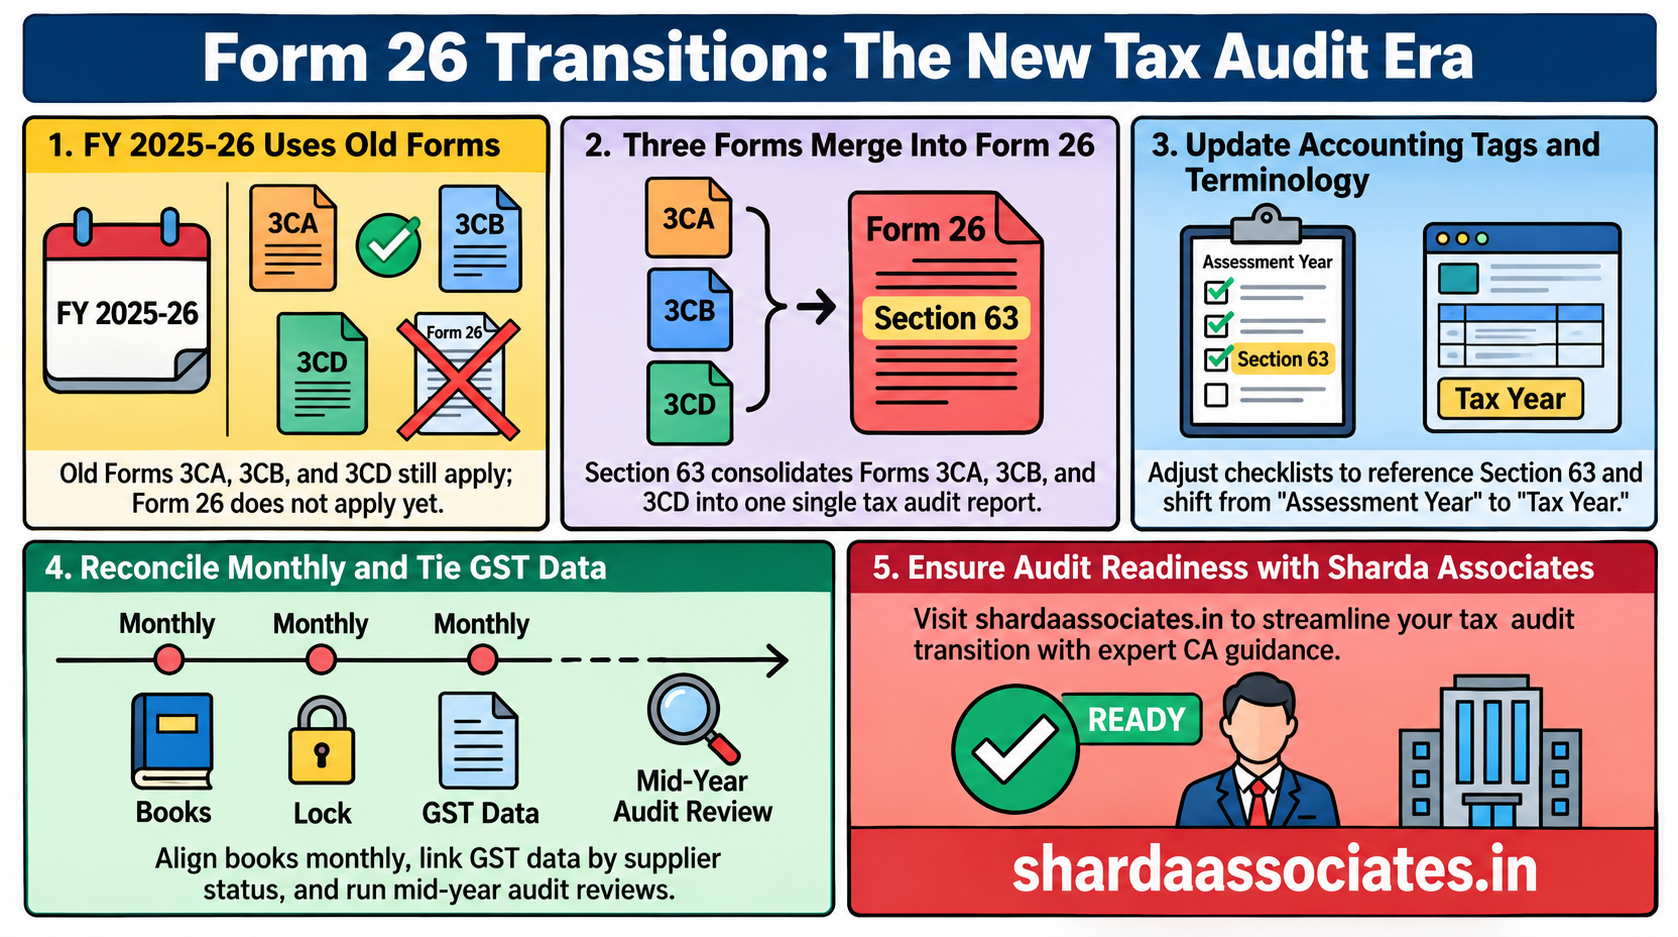
Short answer: From Tax Year 2026-27 (income from 1 April 2026), the tax audit report under Section 63 of the Income-tax Act, 2025 is a single Form 26, replacing Forms 3CA, 3CB and 3CD. Section 63 broadly corresponds to Section 44AB of the 1961 Act. For the year just ended, FY 2025-26 (AY 2026-27), the old Forms 3CA/3CB with 3CD still apply.
Reports describe the audit thresholds as carried over, but the form structure and section references change. Many businesses heard “Form 3CD is gone” and assumed it affects the audit they are completing now. It does not. The change is real, but it starts one year later, and mixing the two years is the most common mistake in the transition.
Sharda Associates is a CA-led firm that has prepared over 45,500 CA-certified reports. Tax audit figures sit next to GST returns and financial statements in loan files, so a clean transition matters to lenders as well as to the tax department.
Which Form Applies to Which Year?
| Particular | FY 2025-26 (AY 2026-27) | Tax Year 2026-27 |
| Income period | 1 April 2025 to 31 March 2026 | 1 April 2026 to 31 March 2027 |
| Governing Act | Income-tax Act, 1961 | Income-tax Act, 2025 |
| Tax audit provision | Section 44AB | Section 63 |
| Tax audit report | Forms 3CA or 3CB with Form 3CD | Form 26 |
| Due date (generally) | 30 September 2026 | 30 September 2027, as reported |
What Is Form 26?
Form 26 is the single tax audit report prescribed under Section 63 of the Income-tax Act, 2025, read with Rule 47 of the Income-tax Rules, 2026. It merges the earlier Form 3CA (accounts already audited under another law), Form 3CB (no other audit) and Form 3CD (statement of particulars) into one form.
What Actually Changes for Businesses?
- One form for every audit case. Whether or not your accounts are audited under another law, the report is Form 26.
- New section references. Clause and section references in the report follow the 2025 Act, so your working papers and auditor’s checklists need updating.
- New terminology. The Act speaks of the tax year, not the previous year and assessment year.
- Data capture. Information that used to be compiled for 3CD needs to be organised for the new form, so accounting systems and tags should be reviewed.
- Auditor engagement. Engagement letters, audit plans and internal checklists should refer to Section 63 and Form 26 for Tax Year 2026-27.
- Timeline. The first Form 26 reports relate to Tax Year 2026-27 and fall due in 2027, so you have a full year to prepare.
What Does Not Change?
The obligation itself continues: a business that meets the audit conditions must get its accounts audited by a chartered accountant and furnish the report on time. Commentary describes the thresholds as unchanged and Section 63 as a renumbering of Section 44AB, but check the conditions for your own case, since they depend on turnover, receipts and the way you are taxed.
What Should You Do If You Are Still Finishing the FY 2025-26 Audit?
Use Forms 3CA/3CB and 3CD, not Form 26. The due date was generally 30 September 2026. Reports indicate that a notification extended the date to 21 October 2026 for a specified category, so check the notification and whether it covers you before you rely on it.
How Can You Prepare for Tax Year 2026-27?
- Keep the books closed and reconciled monthly, not only at year end
- Maintain records of the data a tax audit report usually needs, such as TDS compliance, cash transactions, loans and deposits, related-party transactions and payments to micro and small enterprises
- Keep GST data tied to the books, including the break-up of expenditure by registered and unregistered suppliers
- Review your accounting software and tags with your auditor
- Agree a calendar with your auditor, with a mid-year check and a draft well before the due date
What Might a Preparation Calendar Look Like?
A simple plan for the first Form 26 year:
- Now to December 2026: confirm whether the audit applies to you for Tax Year 2026-27 and update accounting tags and checklists
- January to March 2027: run a mid-year review of TDS, cash transactions, loans and related-party items, and fix gaps while they are small
- April to June 2027: close the books, reconcile GST and prepare schedules
- July to August 2027: give your auditor a complete, reconciled set of records
- September 2027: review the draft well before the reported due date and keep time for corrections
The dates are a planning aid, not statutory dates, so confirm the due date for your case closer to the time.
Which Mistakes Are Common in the Transition?
- Using the AY 2026-27 and Tax Year 2026-27 labels interchangeably
- Starting Form 26 workings for the audit that is still on Form 3CD
- Citing old section numbers in new-year documents
- Leaving data collection to the last month
Conclusion
The shift from Forms 3CA, 3CB and 3CD to Form 26 is mainly a change of structure and references, not of purpose. The practical question is not the form, it is whether your books and records can produce the information the form asks for without a scramble.
The year you have is the advantage. Reconciling monthly, tying GST to the books and agreeing a calendar with your auditor will make the first Form 26 a routine report instead of a new project.
If you would like help reviewing your readiness for the tax audit under Section 63, call Sharda Associates on +91 89899 77769. Outcomes depend on the facts, so no result can be promised.
Frequently Asked Questions
1. What is Form 26? The single tax audit report under Section 63 of the Income-tax Act, 2025, replacing Forms 3CA, 3CB and 3CD.
2. When does Form 26 apply? From Tax Year 2026-27, that is income from 1 April 2026.
3. Which form applies to FY 2025-26? Forms 3CA/3CB with Form 3CD, because FY 2025-26 is governed by the 1961 Act.
4. Which section replaces Section 44AB? Section 63 of the Income-tax Act, 2025.
5. Have the audit thresholds changed? Commentary reports them as carried over, but check the conditions for your case.
6. When is the first Form 26 due? Reported as 30 September 2027 for Tax Year 2026-27. Confirm current dates.
7. Is there an extension for FY 2025-26? Reports mention an extension to 21 October 2026 for a specified category. Check the notification.
8. Does the tax year replace the assessment year? The new Act uses tax year terminology, so use the correct label for each period.
9. What should I do to prepare? Keep books reconciled, organise audit data, tie GST to books and agree a calendar with your auditor.
10. Who certifies Form 26? A chartered accountant, as with the earlier forms.