Quick Answer A bank asks for a monthly stock statement because a cash credit limit is secured by your current assets, mainly stock and receivables, which change every month. The statement shows the...
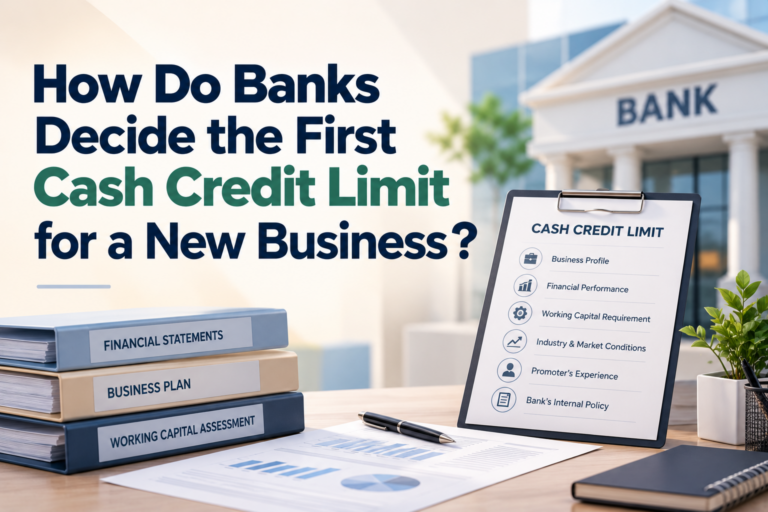
Quick Answer For a new business, banks usually decide the first cash credit limit from the projected working capital requirement in your project report and CMA data, not from past sales. The bank...
Quick Answer A moratorium is a period after the MSME term loan is sanctioned during which you do not have to repay the principal. It is meant to give a new or expanding unit time to set up machinery...
Quick Answer If your stock statement shows less stock and receivables than your cash credit (CC) limit needs, your drawing power falls below the sanctioned limit. You can then withdraw only up to the...
Short answer: In most cases, yes. A moratorium usually pauses the repayment of the principal, not the interest. Whether you pay the interest every month or it gets added to your loan depends on your...
Short answer: Yes, in many cases. A bank can sanction a term loan for machinery and a separate working capital limit, such as cash credit, in the same proposal. Some banks also offer a composite loan...
Short answer: Sometimes, yes. Some banks may count money you have already spent on plant and machinery, either as your own contribution (margin money) or, in a few cases, as an amount to be...
Short answer: Yes, it is possible. Banks do sanction a second term loan to a running business, but only if the first loan is being repaid regularly and the business can afford both instalments. The...
Short answer: The existing cash credit limit does not increase on its own. When a business expands, its stock and receivables usually grow, so it needs more working capital. You have to ask the bank...