Once you hand over your application and documents, the process can feel like a black box — you wait, sometimes for weeks, without a clear sense of what’s actually happening on the bank’s side. In reality, every business loan application moves through a fairly consistent internal sequence: document verification, credit appraisal, sanction, documentation, and disbursement. Understanding each stage helps you know what’s normal, what’s a delay worth following up on, and where good documentation — particularly your project report or CMA data — actually speeds things up. At Sharda Associates, we prepare the exact documents that move a file through this pipeline faster, so here’s a realistic walkthrough of what happens after you submit.
Stage 1: Document Verification (Typically 2–4 Working Days)
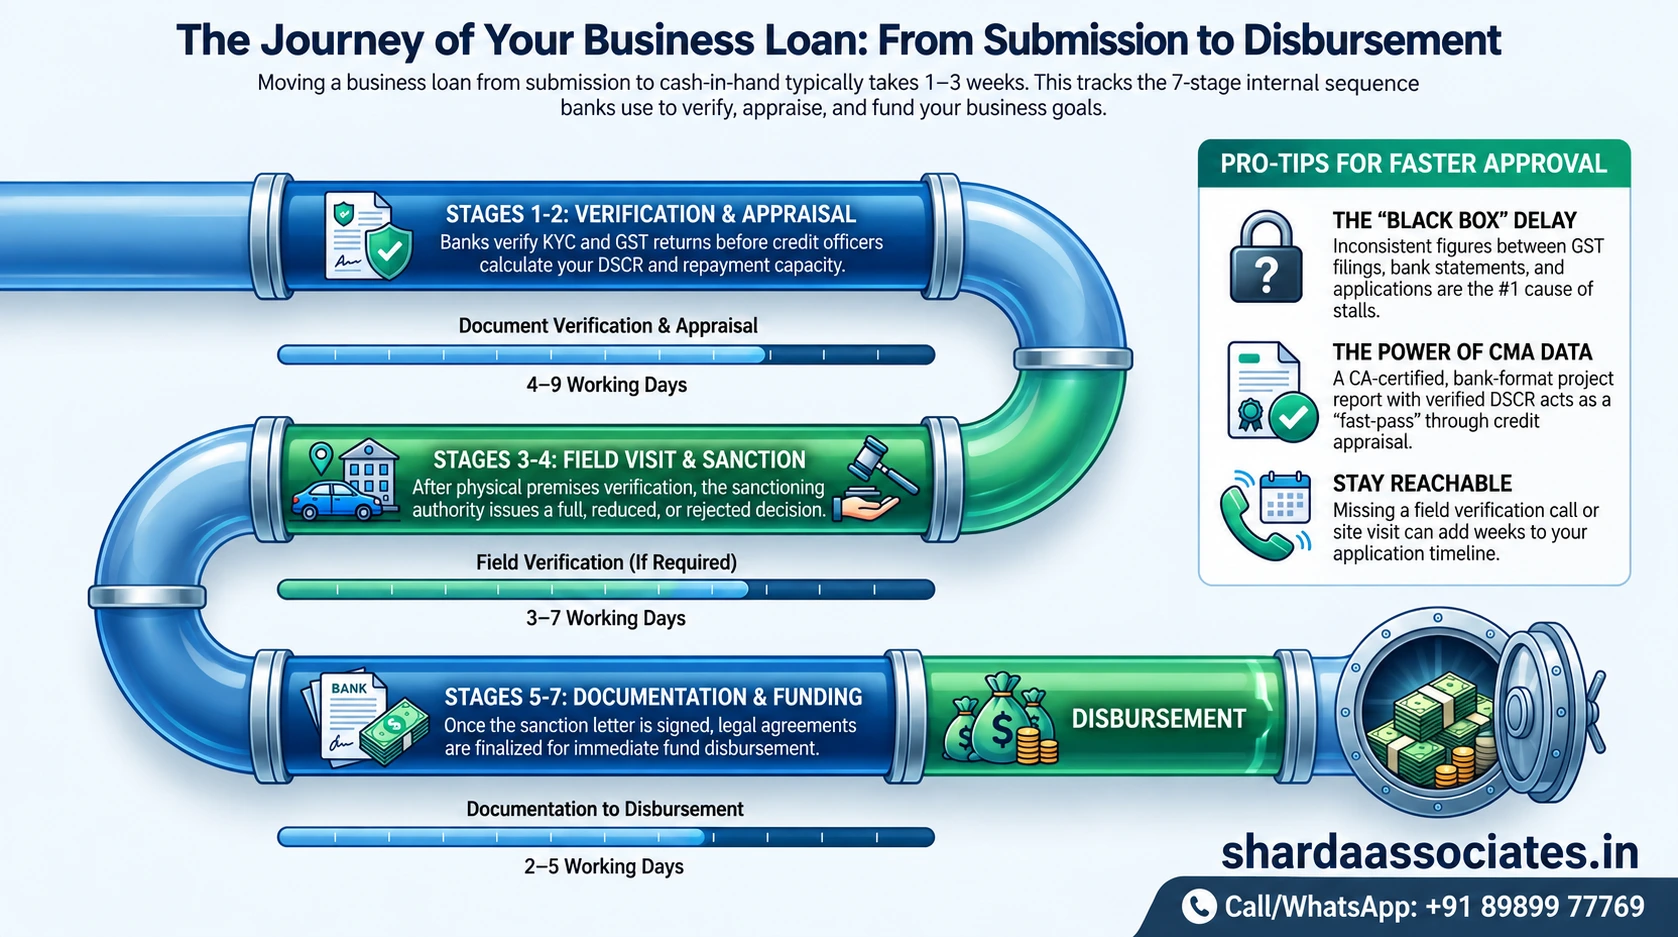
The bank first checks that your application is complete — KYC, business registration, bank statements, ITR or GST returns (where applicable), and your project report or CMA data. Missing or inconsistent documents at this stage are one of the most common reasons files stall before they even reach the credit team.
Stage 2: Credit Appraisal and Risk Assessment (Typically 2–5 Working Days)
This is where the credit officer evaluates your repayment capacity in detail:
- DSCR calculation — checking whether your projected income comfortably covers the proposed EMI.
- Turnover and cash flow verification — cross-checking your declared turnover against bank statements and GST filings.
- Credit score and repayment history review — pulling your CIBIL report and checking for defaults, settlements, or irregular repayment patterns.
- Margin money/promoter contribution check — confirming your own contribution meets the bank’s norms for that loan category.
- Collateral valuation, if the loan is secured — a property or asset valuation may be conducted in parallel.
For scheme-linked loans (PMEGP, MUDRA, CGTMSE), this stage also includes checking that your application meets the specific scheme’s eligibility criteria.
Stage 3: Field Verification (Where Applicable)
For many business loans — especially new units, PMEGP applications, or higher-ticket term loans — the bank or a third-party agency conducts a physical verification of your business premises, checks stock or machinery where relevant, and may interview the promoter directly. This step can add several days depending on scheduling and location.
Stage 4: Sanction Decision
Once the credit appraisal is complete, the file moves to a sanctioning authority — this could be the branch manager, a regional credit committee, or a scheme authority (like KVIC/DIC for PMEGP), depending on the loan amount and type. The outcome is one of three:
- Full sanction at the requested amount.
- Reduced sanction, based on DSCR, margin or documentation factors.
- Rejection, with or without a stated reason.
Stage 5: Sanction Letter
If approved, you receive a sanction letter specifying the loan amount, interest rate, tenure, processing fees, and any conditions attached. This is the point to carefully review every term — the amount, rate, repayment schedule, and prepayment charges — before accepting, since these details are also required to be disclosed in the Key Fact Statement (KFS).
Stage 6: Documentation and Agreement Signing (Typically 1–2 Working Days)
After you accept the sanction letter, the bank prepares the formal loan agreement, along with any security creation (for secured loans) and a NACH mandate for EMI collection. This is largely a legal and administrative step rather than a fresh credit review.
Stage 7: Disbursement (Typically 1–3 Working Days After Documentation)
Once all formalities are complete, the sanctioned amount is transferred to your business account — either as a single lump sum (common for term loans) or in tranches (common for construction-linked or working capital facilities). Some lenders disburse directly to a third party, such as an equipment supplier, if that was specified in the loan purpose.
Typical Overall Timeline
| Stage | Approximate Duration |
| Document verification | 2–4 working days |
| Credit appraisal | 2–5 working days |
| Field verification (if applicable) | Varies, often 3–7 days |
| Sanction to agreement signing | 1–2 working days |
| Disbursement after documentation | 1–3 working days |
Overall, most business loan applications move from submission to disbursement in roughly 1–3 weeks, though scheme-linked loans (PMEGP, CGTMSE) and larger term loans can take longer due to additional approval layers.
What Can Delay the Process
- Incomplete or inconsistent documents at submission.
- A project report or CMA data that doesn’t follow the bank’s expected format, triggering queries.
- Mismatches between GST-declared turnover, bank statements and the figures in your application.
- Scheduling delays for field verification.
- Additional queries from the credit committee on DSCR or margin money.
What You Can Do to Keep Your File Moving
- Submit a complete, internally consistent document set the first time — this avoids the most common cause of delay.
- Ensure your project report/DPR and CMA data are CA-certified and follow the bank’s standard format, with a verified DSCR.
- Respond quickly to any verification calls or requests for clarification.
- Keep your bank account active and be reachable for the field verification visit.
Conclusion
The gap between submitting your application and seeing money in your account isn’t a black box — it’s a fairly predictable sequence of verification, appraisal, sanction and disbursement, and most delays trace back to something specific in the documentation rather than the process itself. A well-prepared, bank-format project report or CMA data with a properly calculated DSCR is usually the single biggest lever for moving a file through faster. Our CA team at Sharda Associates prepares exactly this kind of bank-ready documentation daily. Call or WhatsApp us at +9189899 77769 if you’d like your application file reviewed before submission or need help understanding where a pending application currently stands.
Frequently Asked Questions
1. What happens after I submit my business loan application to the bank?
After submission, the bank generally verifies your application and documents, checks credit history, reviews financial information, evaluates the business and project, and may conduct a site visit before making a sanction decision.
2. How long does a business loan take after application submission?
The processing time varies depending on the lender, loan amount, applicant profile, documentation, and complexity of the business. Complete and consistent documents can help avoid unnecessary processing delays.
3. Will the bank verify my documents after submitting the loan application?
Yes. Banks may verify documents such as KYC records, bank statements, GST returns, income-tax returns, financial statements, business registration documents, and project-related documents.
4. Does the bank check the applicant’s credit score after application submission?
Yes. Credit history is generally an important part of loan assessment. The lender may review the applicant’s credit profile, existing loans, repayment history, outstanding obligations, and other credit-related information.
5. Does the bank verify the business turnover mentioned in the application?
The lender may compare declared turnover with available financial records, including bank statements, GST returns, income-tax returns, and financial statements, depending on the loan and lender’s requirements.
6. Can the bank ask for additional documents after submitting the application?
Yes. If information is incomplete, unclear, outdated, or requires further verification, the bank may request additional documents or clarification before completing its assessment.
7. Why does a bank conduct a site visit after receiving a business loan application?
A site visit may help the lender verify the existence and operations of the business, location, infrastructure, machinery, stock, activity level, and other information relevant to the loan assessment.
8. What is credit appraisal in a business loan?
Credit appraisal is the lender’s assessment of the applicant’s repayment capacity, business performance, financial position, credit history, proposed loan requirement, and associated risks before making a lending decision.
9. How can Sharda Associates help after submitting a business loan application?
Sharda Associates can help businesses prepare and review important loan documentation, including CA-certified project reports, detailed project reports, financial projections, feasibility reports, and other business documentation, helping applicants present their proposal in a structured and consistent manner.
10. Can Sharda Associates help if the bank asks for a revised project report?
Yes. Sharda Associates can assist in reviewing the lender’s requirements and preparing or updating the project report and financial projections based on the information and documentation provided by the applicant.