A project report for a bank loan explains a proposed or existing business, its investment requirements, expected financial performance and repayment plan. Depending on the lender, loan type and applicable scheme, the report may be prepared by the business owner, consultant, financial professional or Chartered Accountant, and specific certification may be required in some cases. This guide explains who prepares project reports, what information they contain, what documents are needed and how businesses can choose the right professional for their requirements.
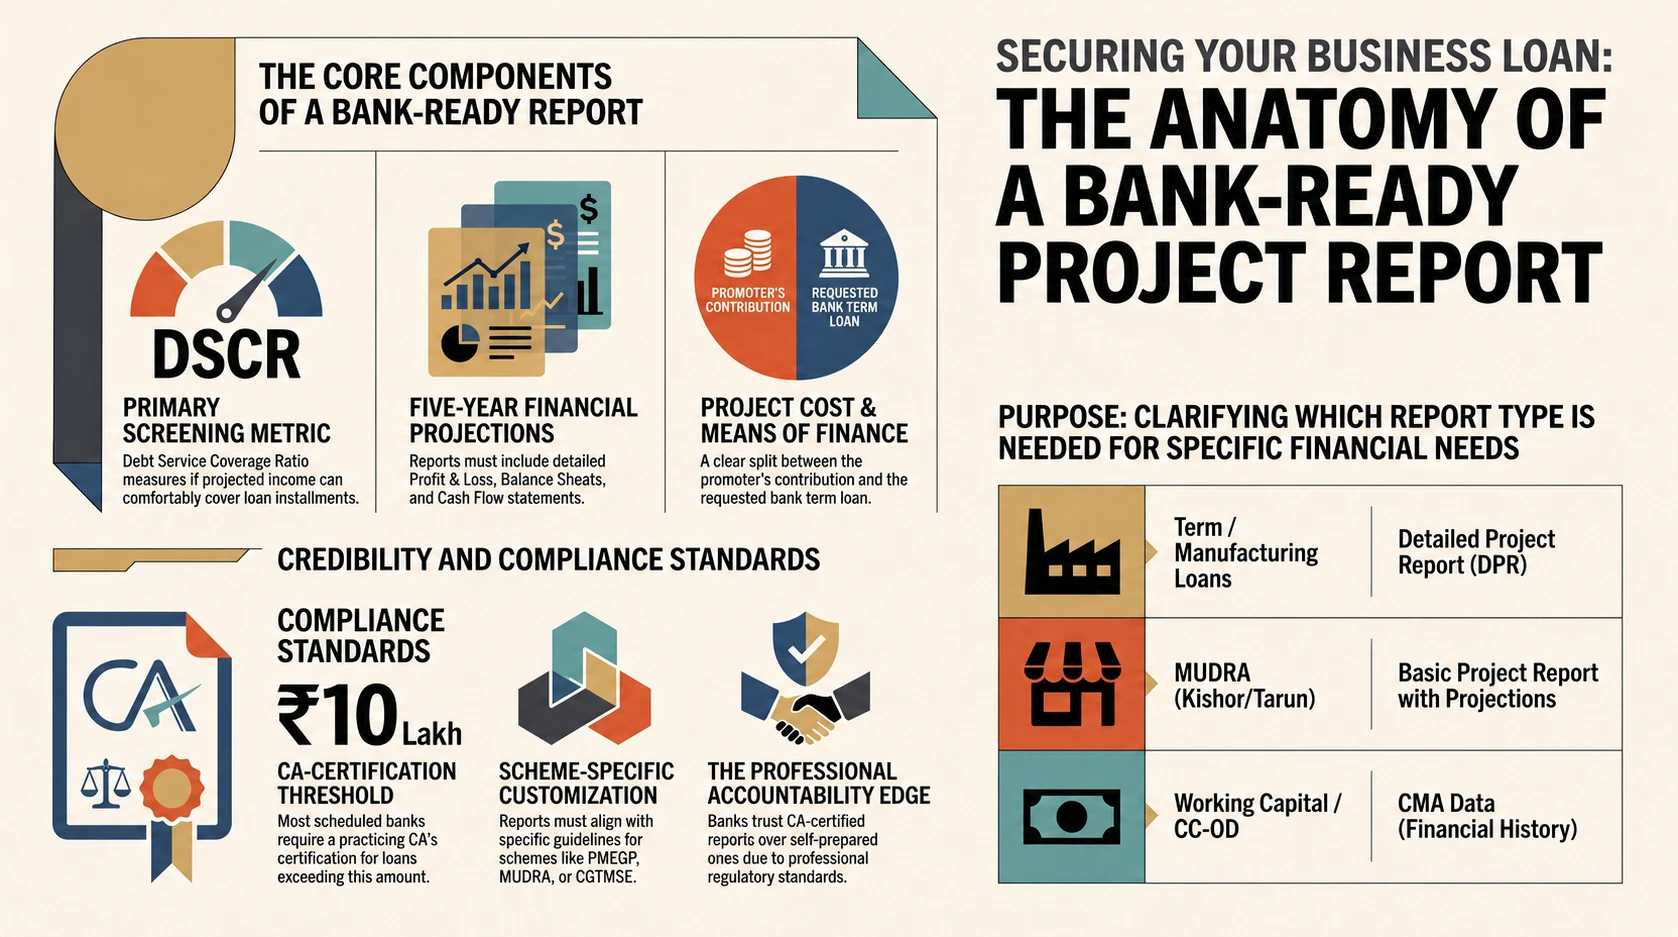
Project report preparation for a bank loan is a technical and financial document that details your company’s expenses, funding strategy, anticipated revenue, and ability to repay the loan. Most scheduled banks require the certification of a practicing chartered accountant for loans over approximately ₹10 lakh.
At Sharda Associates, our CA-led team prepares bank-ready, CA-certified project reports for term loans, MUDRA, PMEGP and other scheme-based lending, so this article explains exactly who is qualified to prepare one, what it should contain, and how to avoid the mistakes that get applications sent back.
Who Can Prepare a Project Report for a Bank Loan?
A project report can be prepared by the business owner, project consultant, financial professional or Chartered Accountant, depending on the complexity and purpose of the project. For a simple business proposal, the promoter may prepare basic information themselves. A detailed manufacturing, expansion or finance proposal may require technical analysis, financial projections and professional assistance.
- Chartered Accountants (CAs) are the most well-known preparers. When certification is necessary, a CA can sign the report with their ICAI membership number and stamp after compiling and reviewing the financial predictions. Banks trust CA-certified reports more than self-prepared ones because this certification entails professional accountability; a CA who approves of inaccurate or unrealistic data may face regulatory action.
- CMA consultants and financial analysts The underlying financial accounts usually still require CA involvement; however, they frequently help with Credit Monitoring Arrangement (CMA) data, a defined format used mostly for working capital constraints and larger term loans.
- Business/industry consultants may provide the non-financial sections, such as market analysis, technical viability, and promoter background, although banks typically do not use these sections in place of CA-certified financials.
- Software-generated or self-prepared reports are accepted for extremely tiny ticket sizes by certain smaller lenders, but because there is no professional standing behind the numbers, there is a greater chance that they will be rejected.
What Does a Bank Loan Project Report Include?
Regardless of who prepares it, a report banks consider “complete” usually covers:
| Section | What it explains |
|---|---|
| Business Profile | Nature of business and promoter details |
| Product/Services | What the business will sell or manufacture |
| Market Analysis | Target customers and market opportunity |
| Project Cost | Machinery, building, equipment and other investment |
| Means of Finance | Promoter contribution and proposed finance |
| Manufacturing/Operations | Production process and operating requirements |
| Manpower | Employees and estimated personnel cost |
| Sales Projections | Expected sales and revenue |
| Profitability | Expected income and operating expenses |
| Cash Flow | Expected inflows and outflows |
| Repayment Analysis | Ability to service proposed debt |
Note that requirements vary by lender and scheme, so it’s worth confirming the exact format with your bank or the scheme’s guidelines before submission.
Which Loan Types and Schemes Require a Project Report?
- MUDRA (PMMY) loans — When the loan amount exceeds the smallest bracket, most banks require at least a basic project report with estimates under the Shishu, Kishor, and Tarun categories.
- PMEGP/CMEGP — administered by KVIC and state-level bodies, these applications require a project report as part of the online submission before bank screening.
- CGTMSE-backed collateral-free loans — need the report to also justify MSME classification.
- Term loans and manufacturing/expansion loans — almost always require a Detailed Project Report (DPR), especially above ₹10 lakh.
- Working capital / CC-OD limits – typically rely more on CMA data than a fresh project report, since these are for existing businesses with a financial track record.
How Much Does It Cost to Get One Prepared?
Fees differ based on the type of business, loan size, complexity of the project, and whether it’s a new venture or an established company looking to grow. For smaller MUDRA or PMEGP loans, basic CA-certified project reports are typically less expensive, but thorough, multi-year DPRs for bigger term loans are more expensive since they require additional financial modelling and scheme-specific customisation. Instead of depending on a general estimate, it is preferable to obtain a same-day quote based on your target bank and loan amount.
Common Mistakes That Get Reports Rejected
- Using a generic template instead of customising the report to the specific bank or scheme’s format.
- Overstating projected sales or margins without realistic assumptions — credit officers are trained to spot this.
- Missing or inconsistent DSCR calculation, which is often the first thing a screening officer checks.
- Skipping CA certification on loans where the bank expects it, leading to the file being returned before evaluation even begins.
- Ignoring scheme-specific formats — for instance, submitting a plain DPR where a PMEGP-specific report is required.
Why CA Certification Matters
The bank is informed by a CA’s certification that the data and assumptions have been compared to standard accounting and lending standards by a trained, ICAI-registered professional. A fully certified, realistic report greatly lowers the likelihood that your file will be denied on the basis of documents alone, but it does not guaranty loan approval—approval always rests on the bank’s own credit evaluation, your ability to repay, and scheme eligibility. An ICAI-registered chartered accountant at Sharda Associates prepares and certifies our project reports, which are tailored to the particular bank or scheme rather than being constructed from a pre-made template. DSCR is verified prior to distribution.
Call us at +91 89899 77769 to check your eligibility and get your application ready.
Frequently Asked Questions
Q1. Who can prepare a project report for a bank loan?
A project report can be prepared by the business owner, consultant, financial professional or Chartered Accountant depending on the project and lender requirements. If professional certification is specifically required, the report should be prepared and certified according to that requirement.
Sharda Associates provides CA-led project report preparation covering the financial and project information required for the proposed funding purpose.
Q2. What is included in a bank loan project report?
A bank loan project report generally includes the business profile, product or service details, market analysis, project cost, means of finance, machinery or infrastructure, working capital, sales projections, profitability, cash flow and repayment analysis.
Sharda Associates structures these details according to the proposed business and funding requirement.
Q3. What documents are required for project report preparation?
Documents may include promoter details, business registration information, machinery quotations, land or building details, financial statements, bank statements, GST information and proposed investment details. The exact requirements vary according to the project and lender.
Sharda Associates helps businesses identify and organise the relevant information required for preparing the report.
Q4. How much does it cost to prepare a project report?
The cost depends on the business type, project size, loan requirement, technical analysis and financial modelling involved. A detailed manufacturing DPR generally requires more analysis than a simple business proposal.
Sharda Associates provides project report preparation based on the scope and requirements of the specific project.
Q5. How long does it take to prepare a project report?
The preparation time depends on the complexity of the project and how quickly the required information and documents are available. Manufacturing and large investment projects may require more analysis than simple proposals.
Sharda Associates works with the information provided by the entrepreneur to prepare the report according to the scope of the project.
Q6. Does a CA-certified project report guarantee a bank loan?
No. CA certification does not guarantee loan approval. The lender makes the final decision after evaluating the applicant, project feasibility, financial projections, repayment capacity and other applicable lending conditions.
Sharda Associates provides CA-led project report preparation and financial analysis, while the final lending decision remains with the concerned bank or authority.
Q7. Can Sharda Associates prepare a project report according to bank requirements?
Yes. Sharda Associates can prepare project reports according to the proposed business, funding purpose and applicable lender or scheme requirements. Depending on the project, the report can include project cost, means of finance, working capital, projected financial statements, profitability and repayment analysis.
Q8. What is the difference between a project report and a Detailed Project Report?
A project report explains the key aspects of a business proposal and its financial requirement. A Detailed Project Report generally provides more extensive technical, operational, market and financial analysis, particularly for larger or more complex projects.
Sharda Associates can prepare the appropriate report format according to the project’s size, purpose and funding requirement.